
South Carolina Auto Repair and Garage Insurance

CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

Hospital bills, treatment, and prescriptions for a work-related injury or illness.

Medical expenses

Claims history

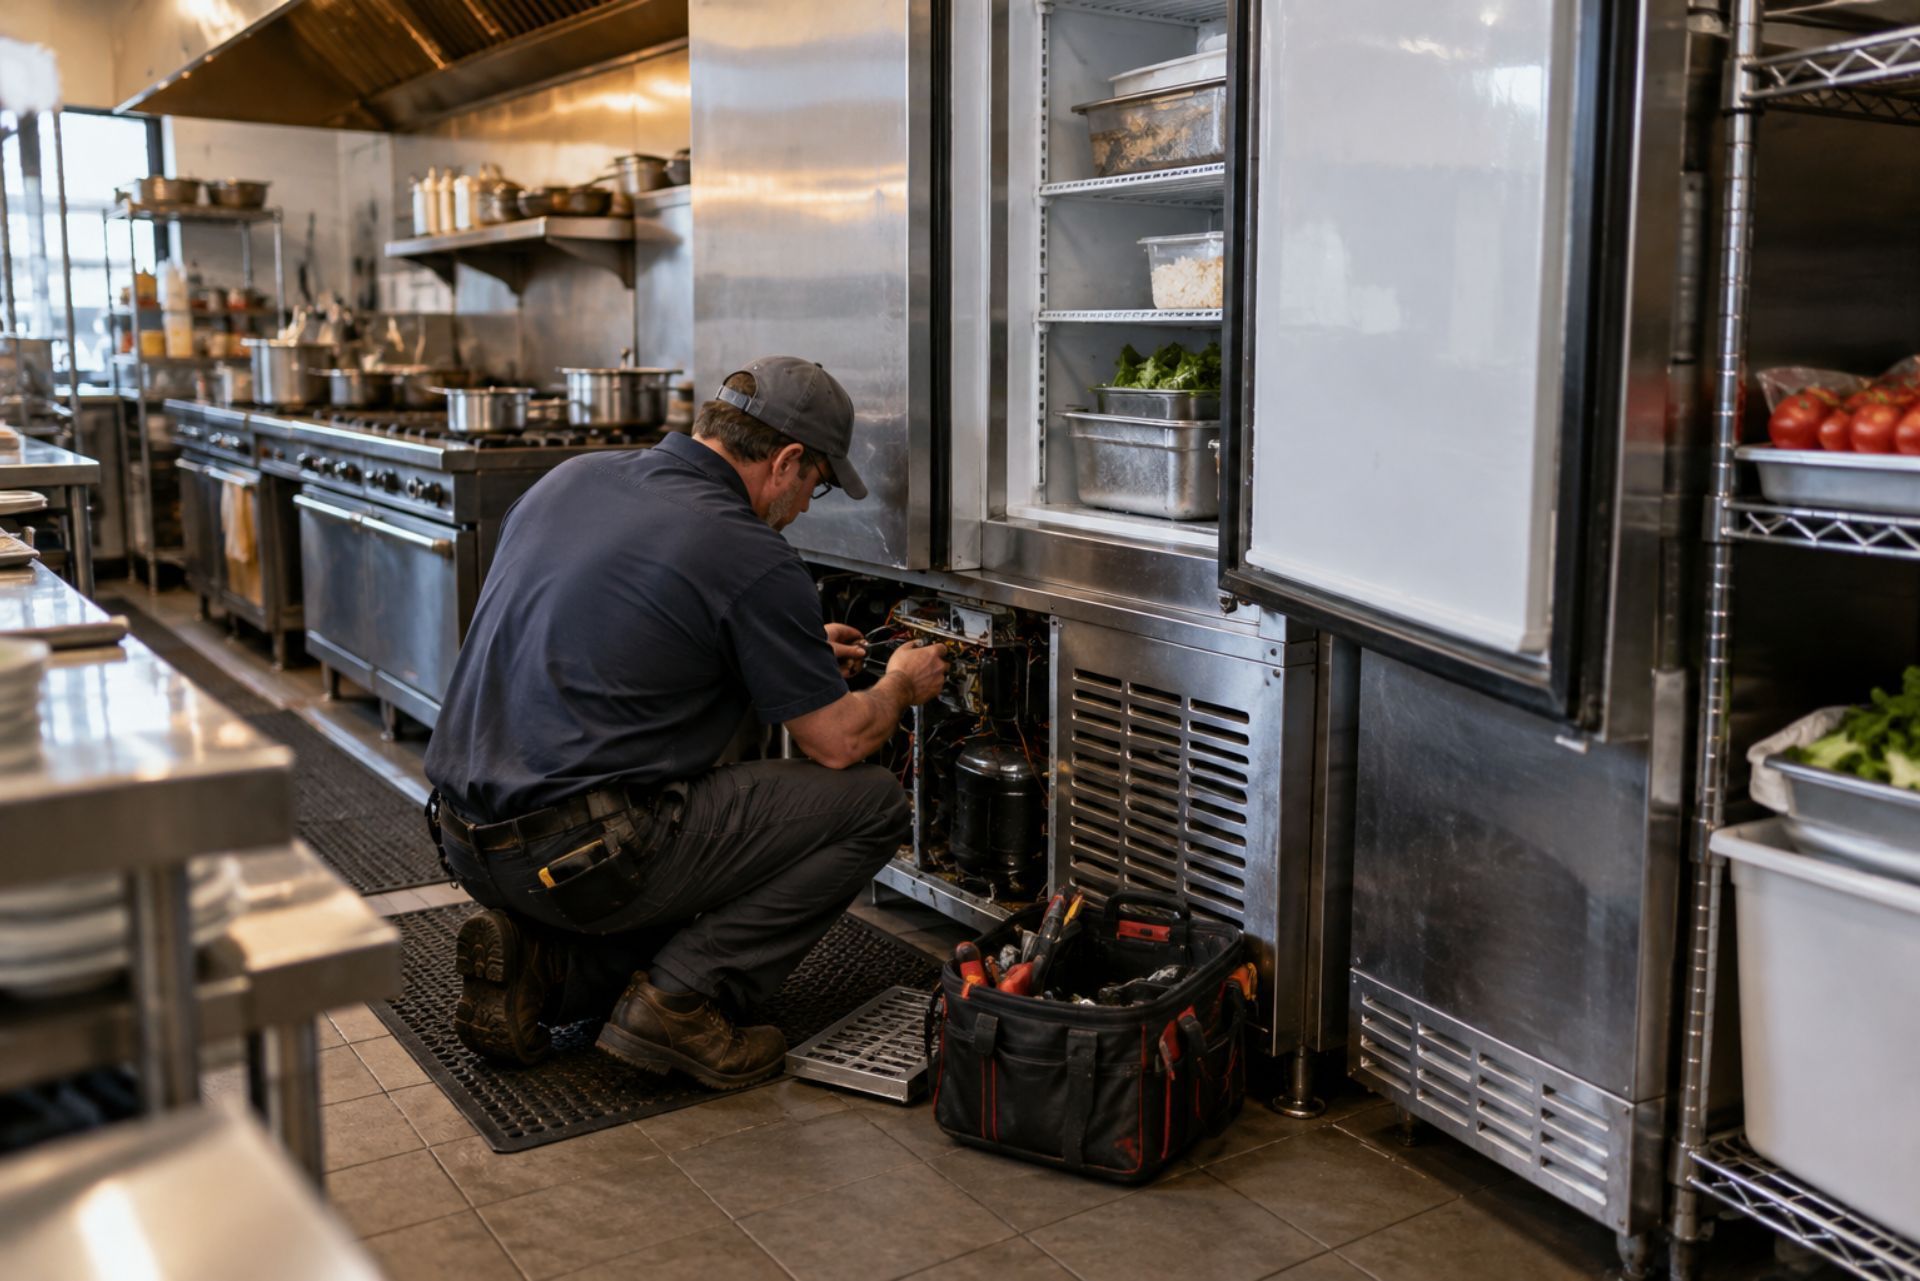
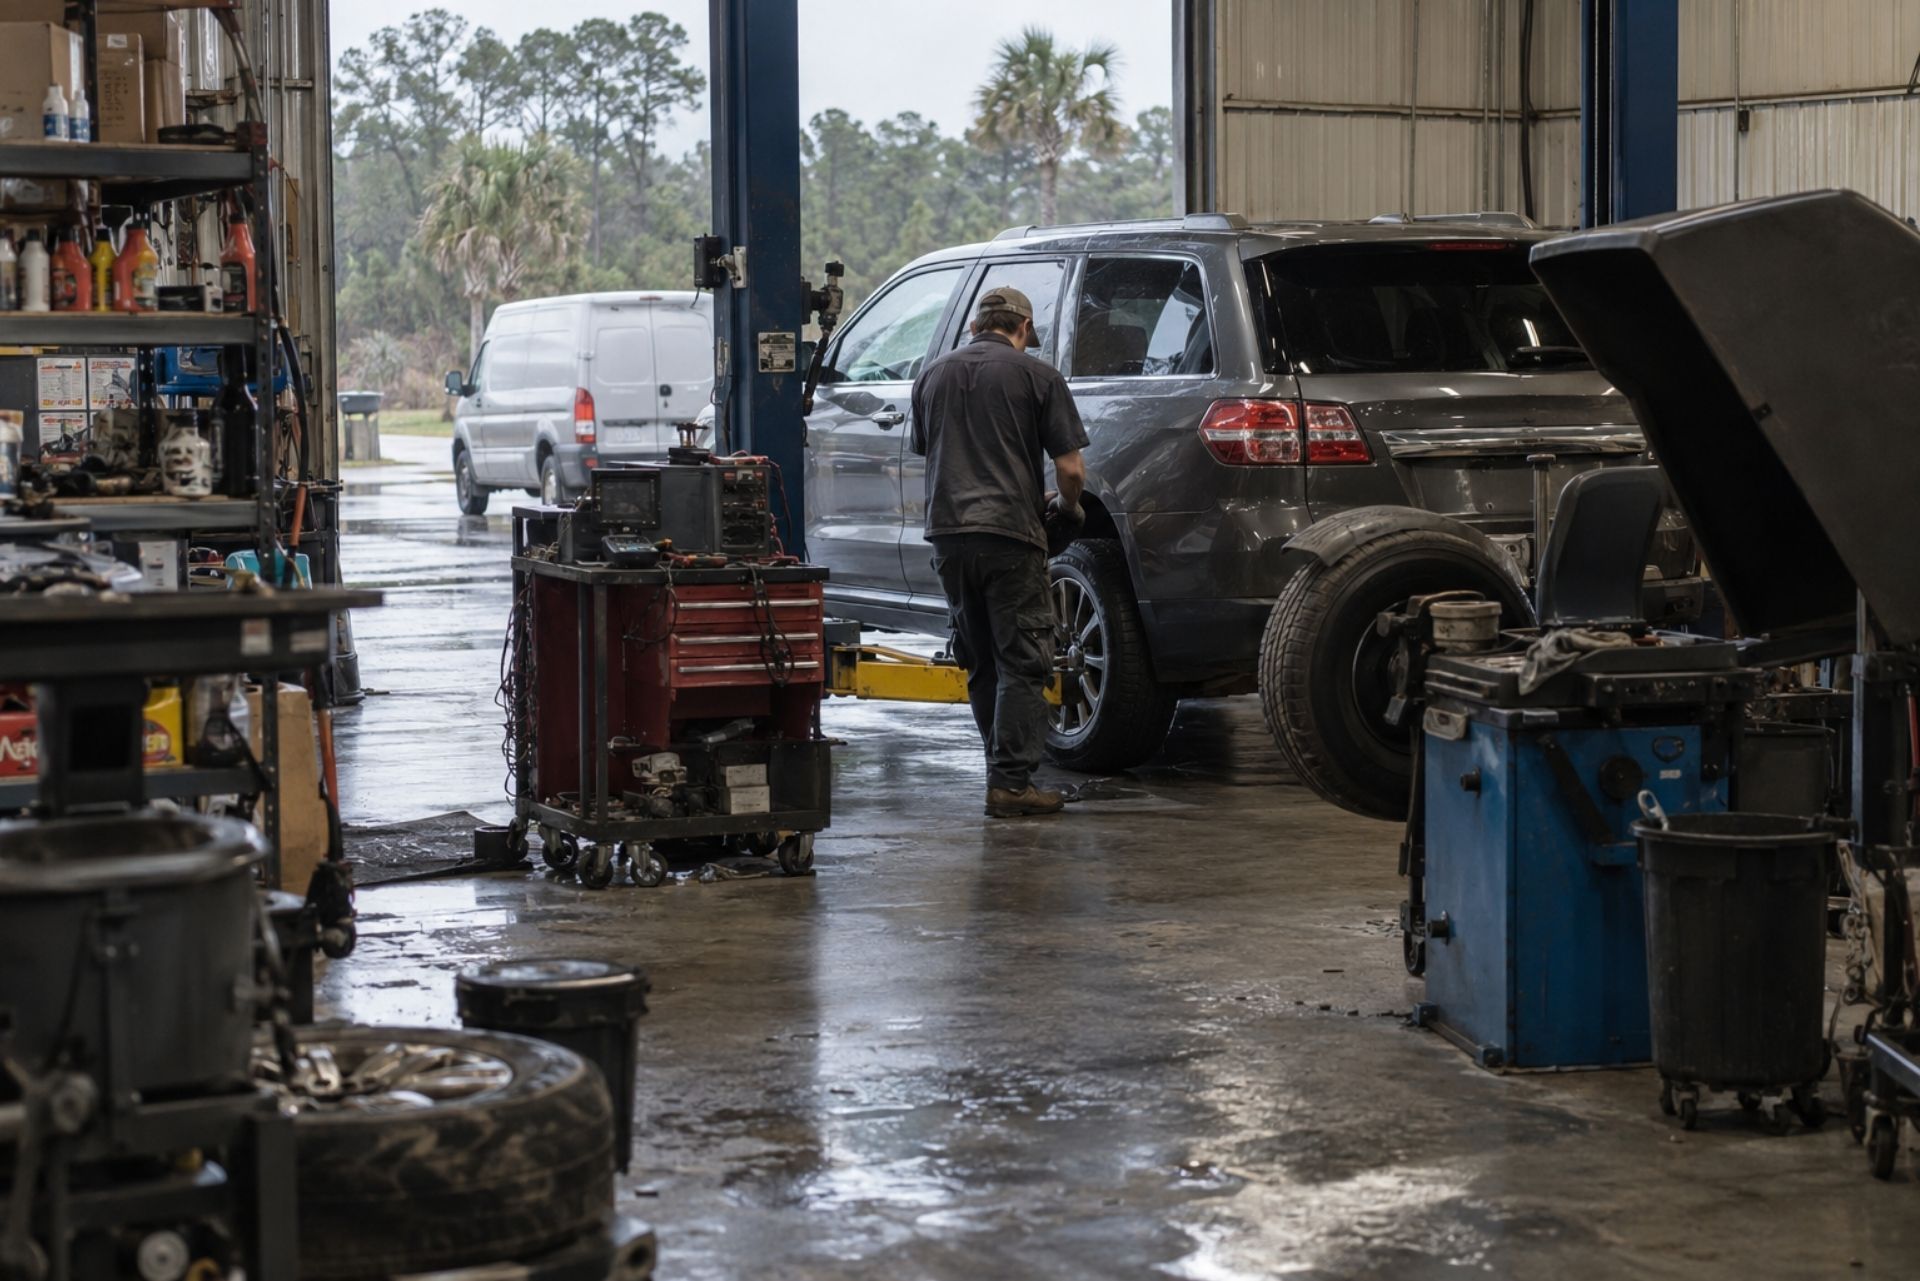
Running an auto repair shop in South Carolina means managing risks most business owners never think about: a customer's car gets damaged during a test drive, a hydraulic lift fails and injures a technician, or a storm rips through your building and destroys $50,000 worth of diagnostic equipment. The right insurance setup is the difference between absorbing these hits and closing your doors. But garage insurance isn't a single policy you buy off the shelf. It's a collection of coverages, each designed to protect a different piece of your operation, and getting the mix wrong can leave expensive gaps. Whether you're running a two-bay shop in Florence or a full-service collision center near Myrtle Beach, understanding how garage liability, garagekeepers coverage, property protection, tools insurance, and workers' compensation fit together is essential. South Carolina has its own regulatory quirks, too, from state-mandated auto liability minimums of 25/50/25 to coastal wind and hail exposure that can spike your premiums. This guide breaks down each coverage type, what drives your costs, and how to build a policy package that actually matches the risks your shop faces every day. The goal isn't to sell you on the most expensive plan available: it's to help you understand what you're buying and why.

Essential Insurance Coverage for South Carolina Garage Owners

A garage operation faces a unique blend of risks that standard business insurance doesn't cover well. You're storing other people's vehicles, operating heavy equipment, handling flammable materials, and sending cars out on test drives. Each of those activities creates a distinct liability, and each one needs its own coverage response.


The core insurance stack for most SC auto repair shops includes five to six policies working together. Garage liability handles third-party injury and damage claims. Garagekeepers insurance covers damage to customer vehicles in your care. Commercial property protects your building and contents. Inland marine or tools coverage insures your specialized equipment. And workers' compensation, which South Carolina requires for businesses with four or more employees, protects your team. Skipping any one of these creates a hole that a single bad week can exploit.

Garage Liability vs. Garagekeepers Insurance

These two coverages sound similar, and shop owners confuse them constantly, but they protect completely different things. Garage liability is your version of general liability and commercial auto insurance combined into one policy. It covers bodily injury or property damage claims from third parties: a customer slips on an oil stain in your lot, or a mechanic causes an accident while test-driving a client's car. It also covers your owned business vehicles.


Garagekeepers insurance is entirely separate. It specifically covers damage to vehicles your customers have left with you. If a fire breaks out overnight and destroys three cars sitting in your bays, garagekeepers pays for those vehicles. If a tree falls on a customer's truck parked in your lot during a storm, same thing. Without this coverage, you'd be personally liable for replacing or repairing those vehicles out of pocket. In South Carolina, where hurricane season and severe thunderstorms are annual realities, this coverage is non-negotiable.


The key distinction: garage liability covers claims against you for harm to others. Garagekeepers covers damage to property you're temporarily responsible for. You need both.

Protecting Commercial Property and Specialized Tools

Your building, lifts, compressors, scan tools, and alignment machines represent a serious capital investment. Commercial property insurance covers the physical structure (if you own it) and its contents against fire, theft, vandalism, and certain weather events. One thing to keep in mind: standard property policies in coastal South Carolina often exclude wind and hail damage, requiring a separate windstorm policy through the SC Wind and Hail Underwriting Association if you're in a qualifying zone.


Specialized tools and portable equipment often need inland marine coverage, sometimes called a tools and equipment floater. Your standard property policy might cap coverage on mobile items or exclude tools taken off-premises. If you're doing roadside service calls or carrying diagnostic equipment between locations, equipment insurance protects those assets even when they're not sitting in your shop. A single modern diagnostic scan tool can cost $5,000 to $15,000, and most shops have multiple units. That exposure adds up fast.

South Carolina Workers' Compensation Requirements

South Carolina law requires workers' compensation insurance for any business with four or more employees. Auto repair is physically demanding and genuinely dangerous work: burns, crush injuries, chemical exposure, and repetitive strain injuries are common. Even if you only have two or three employees and aren't technically required to carry coverage, going without it is a gamble that could bankrupt a small shop if someone gets seriously hurt on the job.


Workers' comp covers medical expenses, lost wages, and rehabilitation costs for injured employees. It also protects you from lawsuits related to workplace injuries. South Carolina's rates vary by job classification, and auto mechanics typically fall into a higher-risk category than, say, office workers. Your premium is calculated based on payroll size and your experience modification rate, which reflects your claims history. Shops with clean safety records pay significantly less. Small business insurance requirements in South Carolina vary by industry, but workers' comp is one area where cutting corners can trigger state penalties and personal liability.

Your CSP agent

Lawson Walker, CIC

Insurance Sales

CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.

From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Feature Admitted (Standard) Carriers Non-Admitted (E&S) Carriers
State regulation Fully regulated; rates filed with state Exempt from rate filing; flexible pricing
Guaranty fund protection Yes: state fund covers claims if carrier fails No: no guaranty fund backstop
Policy forms Standardized (ISO forms common) Manuscript or custom forms
Risk appetite Prefers low-to-moderate risk Accepts high-risk and unusual exposures
Premium cost Generally lower Typically 20-75% higher
Surplus lines tax Not applicable Buyer pays state surplus lines tax (varies 2-5%)
Speed of placement Standard timelines Can be faster or slower depending on complexity

Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.

Comparing Liability and Physical Damage Protections

Understanding the boundary between liability and physical damage coverage is where most shop owners get tripped up. Liability coverage responds when someone else suffers a loss because of your operations. Physical damage coverage responds when something you're responsible for gets damaged, regardless of fault. Both are critical, but they trigger under different circumstances.


A practical example: your technician accidentally drops a transmission on a customer's hood while removing it. Garagekeepers insurance (physical damage to a customer's vehicle in your care) would cover the repair. But if that same transmission falls on a bystander's foot, garage liability (bodily injury to a third party) kicks in. Same shop, same day, two completely different policies responding. An independent agency like CSP Insurance Services can walk you through these scenarios using your actual operations, which is far more useful than reading policy language in the abstract.

Comparison Table: Garage Liability vs. Garagekeepers Coverage

Feature Garage Liability Garagekeepers Insurance
What it covers Third-party bodily injury and property damage Damage to customers' vehicles in your care
Common claim examples Customer slips in shop; accident during test drive Fire damages parked vehicles; hail dents cars on your lot
Who's protected Your business against outside claims Customer vehicle owners
Required in SC? Effectively yes, for any operating shop Not state-mandated, but practically essential
Typical triggers Negligence, accidents involving your operations Fire, theft, vandalism, weather, collision
Coverage options Per-occurrence and aggregate limits Direct primary, direct excess, or legal liability

The "coverage options" row for garagekeepers deserves a closer look. Direct primary coverage pays for damage regardless of fault: even if a hailstorm causes the damage and nobody was negligent. Legal liability only pays if you or your employees were at fault. Direct primary costs more but eliminates arguments about who caused what, which saves you from drawn-out disputes with angry customers.

Factors Influencing Insurance Costs in the Palmetto State

Garage insurance premiums in South Carolina aren't one-size-fits-all. A two-person brake and muffler shop in Rock Hill will pay a fraction of what a 15-employee collision repair center in Charleston pays. The typical annual premium for garage liability starts around $1,300 for smaller operations, but that number can climb quickly based on several factors specific to your business and location.

Business Location and Shop Size

Where your shop sits within South Carolina has a measurable impact on your premiums. Coastal locations near Myrtle Beach or Charleston face higher property and garagekeepers rates because of hurricane and flood exposure. Even shops 20 miles inland can fall within wind-pool zones that require supplemental coverage. Insurance rates vary significantly by city across South Carolina, and the same principle applies to commercial garage policies.


Shop square footage, the number of bays, and whether you store vehicles outdoors or in enclosed structures all factor into your premium calculation. A 10,000-square-foot facility with an open lot holding 30 customer vehicles presents a very different risk profile than a 3,000-square-foot shop with four indoor bays. Insurers also look at your building's age, construction type (frame vs. masonry), and fire protection systems. A shop with a sprinkler system and monitored alarm will typically qualify for meaningful discounts.

Payroll, Annual Revenue, and Claims History

Your workers' comp premium ties directly to your total payroll. More employees doing higher-risk work means a bigger premium. But the number insurers really care about is your experience modification rate, or "mod rate." This score compares your actual claims history against the expected claims for businesses your size in your industry. A mod rate below 1.0 means you're safer than average and you'll pay less. Above 1.0, and you're paying a surcharge.


Annual revenue affects your general liability and garage liability premiums because higher revenue generally means more customer interactions, more vehicles in your care, and more exposure. Claims history is the single biggest controllable factor. One large liability claim can increase your premiums for three to five years. Shops that invest in safety training, proper lift maintenance, and documented procedures tend to see lower costs over time. Homeowners and business insurance costs in South Carolina reflect the state's broader risk environment, but your individual claims record matters more than any state average.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Feature Admitted (Standard) Carriers Non-Admitted (E&S) Carriers
State regulation Fully regulated; rates filed with state Exempt from rate filing; flexible pricing
Guaranty fund protection Yes: state fund covers claims if carrier fails No: no guaranty fund backstop
Policy forms Standardized (ISO forms common) Manuscript or custom forms
Risk appetite Prefers low-to-moderate risk Accepts high-risk and unusual exposures
Premium cost Generally lower Typically 20-75% higher
Surplus lines tax Not applicable Buyer pays state surplus lines tax (varies 2-5%)
Speed of placement Standard timelines Can be faster or slower depending on complexity

Common Questions About SC Auto Repair Insurance

FAQ: What South Carolina Mechanics Need to Know

Do I need garage liability insurance if I'm a mobile mechanic? Yes. If you're working on vehicles for paying customers, you carry liability risk whether you have a physical shop or not. Mobile operations actually face additional exposure since you're working at customer locations where you don't control the environment.


Does my personal auto policy cover test drives of customer vehicles? No. Personal auto insurance excludes vehicles used for commercial purposes. You need garage liability with a garage operations endorsement to cover test drives and vehicle movement as part of your business.


How many employees trigger workers' comp requirements in South Carolina? Four or more employees, including part-time workers. That said, even shops below this threshold should seriously consider voluntary coverage to protect against a single catastrophic injury claim.


Can I bundle all my garage coverages into one policy? Many carriers offer a garage package policy, sometimes called a "garage policy," that combines garage liability, garagekeepers, and some property coverage. Bundling typically saves 10-15% compared to buying each coverage separately. An independent agency can compare bundled and standalone options across multiple carriers to find the best fit.


What happens if a customer's car is stolen from my lot? Garagekeepers insurance with comprehensive coverage would pay for the vehicle's value. Without it, you're personally responsible. Theft claims are actually more common than many shop owners realize, especially for shops without gated lots or surveillance systems.


Does South Carolina require specific insurance for body shops versus general repair? Body shops and collision centers typically face higher premiums due to paint booth fire risk, use of hazardous materials, and higher-value vehicles in their care. The state doesn't mandate different coverage types, but your insurer will price the risk differently.

Specialty Lines: Flood, Earthquake, and Valuable Items

Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.


Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.


Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.

Making the Right Choice for Your Shop

Getting garage insurance right isn't about buying the most expensive package or the cheapest one. It's about matching your coverage to the actual risks your specific shop faces. A shop doing oil changes and tire rotations has a fundamentally different risk profile than one rebuilding engines or doing frame straightening on high-end vehicles.


Start by listing every activity your shop performs, every piece of equipment worth more than $1,000, and every vehicle that sits on your property overnight. That inventory becomes the basis for a coverage conversation that actually means something. CSP Insurance Services, with roots going back to 1939, works as an independent agency across South Carolina, which means they can compare quotes from multiple carriers rather than pushing a single company's products. That independence matters when you're trying to find the right balance between coverage and cost.


If you're opening a new shop, renewing an existing policy, or just wondering whether your current coverage has gaps, the smartest move is getting a professional review of your specific situation. You can request a quote and have a real person walk through your options: no call centers, no chatbots, just someone who understands garage insurance in South Carolina and can tailor a package to your operation.

About the author

Lawson Walker, CIC

I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.


As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.


Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Meet Richard

Most Requested

Core business coverage.

The policies most South Carolina businesses start with.

Commercial Property

Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Workers Compensation

Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.

Commercial Auto

Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

General Liability

Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.

Inland Marine

Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.

Business Owners (BOP)

A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Personal Insurance

Coverage for your home, vehicles, and family.

Protect what matters most with personal policies shopped across our carriers.

Home

Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.

Auto

South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.

Umbrella

When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.

Boat

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.

Condo

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

Get a Quote

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.

Get a Quote

Industries We Serve

Specialized coverage for your industry.

Every industry carries its own risk. We help South Carolina businesses protect what they've built.

Restaurants

Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.

Manufacturers

From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.

Healthcare Providers

Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Commercial Property

Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Meet Richard View all business coverage Get a Quote

Commercial Auto

Get a Quote

Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

How It Works

Getting covered is simple.

Four steps, one real person from start to finish.

Tell us about you

Share a few details about what you need to protect. A real person reviews it.

We compare carriers

We shop options across our carriers to find strong protection at a fair price.

We recommend coverage

We walk you through the policy in plain language and answer every question.

You get covered

Sign with confidence — and we stay on for changes, claims, and yearly reviews.

We compare several carriers to find a policy that fits you, not one company's products.

Multi-carrier choice

Claims advocacy

When a claim happens, we stand in your corner and help move it forward with your carrier.

Local SC roots

We live and work in Florence and understand the risks your community faces because we face them too.

Client Reviews

Why clients choose CSP.

Independent advice, real people, and decades of local roots.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

Get a Quote

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.

Get a Quote

FAQs

Questions, answered.

Straight answers about working with an independent agency.

  • What does an independent insurance agency do?

    An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.

  • Do you cover both personal and business insurance?

    Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.

  • How long has CSP been in business?

    CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.

  • Will I work with a real person?

    Always. No call centers and no chatbots — you work with a local team member who knows your account.

  • Which areas do you serve?

    We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.

  • How do I get a quote?

    Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.

How It Works

Insurance tips & updates.

Plain-language guidance to help you make confident decisions.

South Carolina Workers' Compensation Requirements for Employers: The 4-Employee Rule and Exemptions
21 September 2026
South Carolina workers' comp requirements for 2026 explained: the 4-employee rule, exemptions, contractor classification, penalties, and compliance.
Term vs. Whole Life Insurance in South Carolina: How Much Coverage Costs and Which to Choose
29 August 2026
Compare term vs. whole life insurance in South Carolina, including costs, coverage options, regulations, and tips to choose the right policy for your family.
How Much Does Business Insurance Cost for a Small Business in Florence, SC?
6 August 2026
Learn how much small business insurance costs in Florence, SC, including GL, workers’ comp, property coverage, pricing factors, and ways to save.

We compare several carriers to find a policy that fits you, not one company's products.

80+ years local experience

1939

Serving SC
Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

Get a Quote

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Get a Quote

Get a Quote

Let's find your coverage.

Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.

2420 Hoffmeyer Road, Suite D
Florence, SC 29501

Mon–Fri 8:30am – 5:00pm