
CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
Hospital bills, treatment, and prescriptions for a work-related injury or illness.
Medical expenses
Claims history
A torn rotator cuff during a CrossFit class. A slip on a wet locker room floor. A hurricane that floods your Myrtle Beach studio for three weeks. These aren't hypothetical scenarios for South Carolina gym owners: they're Tuesday. Running a fitness business in the Palmetto State comes with a specific blend of risks that generic business insurance doesn't fully address. Between coastal storm exposure, high-contact training environments, and South Carolina's particular regulatory requirements, gym and fitness studio insurance needs to be tailored carefully. The right mix of general liability, professional liability, property coverage, workers' compensation, and participant injury protection can mean the difference between surviving a bad month and shutting your doors. And the costs? They vary more than most owners expect. This guide breaks down each coverage type, what South Carolina law actually requires, and how to avoid the gaps that catch fitness business owners off guard. Whether you're opening a yoga studio in Columbia or running a boxing gym in Florence, the stakes are real and the details matter.
Why South Carolina Fitness Businesses Need Specialized Coverage
Fitness businesses sit at an uncomfortable intersection of physical risk, expensive equipment, and close customer contact. A retail shop worries about someone tripping near the entrance. A gym owner worries about that plus heavy machinery, bodily strain, personal training advice that could cause harm, and locker rooms full of personal belongings. Standard
commercial policies often leave critical gaps.
Unique Risks for Palmetto State Gym Owners
South Carolina's climate and geography create risks that gym owners in, say, Minnesota don't face. Coastal facilities from Myrtle Beach to Hilton Head deal with hurricane season every year, and even inland locations in Rock Hill or Columbia aren't immune to severe thunderstorms and flooding. Humidity accelerates equipment corrosion and mold growth, which means higher maintenance costs and more frequent property claims.
The state also has a thriving outdoor fitness culture: boot camps on the beach, trail running groups, paddleboard yoga. Each of those activities introduces liability exposures that don't exist inside four walls. If your trainer leads a group run through a public park and someone rolls an ankle on uneven ground, your insurance needs to respond.
South Carolina Legal and Liability Climate
South Carolina follows a modified comparative negligence standard, meaning an injured party can recover damages as long as they're less than 51% at fault. That's a lower bar than some states, which means lawsuits against gym owners have a real chance of succeeding even when the member arguably contributed to their own injury.
Every fitness provider in the state must also maintain a Certificate of Authority from the Department of Consumer Affairs, and facilities offering prepaid contracts over three months or $200 must post a surety bond of up to $50,000. These aren't optional: operating without them can result in fines and forced closure. The regulatory environment here is more structured than many owners realize when they first sign a lease.
Your CSP agent
Lawson Walker, CIC
Insurance Sales
On this page
CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.
From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.
Core Insurance Policies for Local Studios
The foundation of any
fitness business insurance program includes three to four core policies. Skipping any one of them creates a gap that could be financially devastating.
General Liability vs. Professional Liability
General liability covers third-party bodily injury and property damage: a member trips over a dumbbell, a guest slips in the parking lot, or your signage falls and damages a neighboring storefront. It's the broadest, most essential policy.
Professional liability (sometimes called errors and omissions) covers something different entirely: claims arising from your professional advice or instruction. If a personal trainer designs a program that aggravates a client's pre-existing condition, or a nutritional recommendation causes harm, that's a professional liability claim. General liability won't touch it. Most gym owners need both.
Workers' Compensation Requirements in SC
South Carolina requires workers' compensation insurance for businesses with four or more employees. That threshold catches a lot of small studios off guard, especially once you count part-time front desk staff alongside trainers. Independent contractor arrangements don't eliminate this requirement either: if the state determines your "contractors" are actually employees based on how much control you exercise over their work, you're on the hook.
Workers' comp covers medical expenses and lost wages for employees injured on the job. In a gym setting, that could be anything from a trainer pulling a muscle while demonstrating an exercise to a cleaning staff member slipping on a freshly mopped floor.
Property Insurance for Equipment and Facilities
Commercial treadmills run $3,000 to $10,000 each. A full set of functional training equipment can easily exceed $50,000. Property insurance covers this equipment against fire, theft, vandalism, and certain weather events. The good news for South Carolina gym owners: commercial property insurance premiums in the state saw a 1.2% decline in Q1 2026, the first decrease since 2017. That's a small but welcome shift after years of rising costs.
One thing to keep in mind: standard property policies typically exclude flood damage. If your facility is anywhere near the coast or in a known flood zone, you'll need a separate flood policy through the National Flood Insurance Program or a private carrier.
Comparison: General Liability vs. Professional Liability
These two policies get confused constantly, so here's a clear breakdown:
| Feature | General Liability | Professional Liability |
|---|---|---|
| What it covers | Bodily injury, property damage, personal/advertising injury | Claims from professional advice, instruction, or services |
| Example claim | Member slips on wet floor | Trainer's program causes client's herniated disc |
| Who needs it | Every gym, no exceptions | Any facility offering training, classes, or wellness advice |
| Typical limits | $1M per occurrence / $2M aggregate | $1M per occurrence / $1M aggregate |
| Covers participant injury from instruction? | Usually no | Yes |
| Required by landlords? | Almost always | Sometimes |
The mistake I see most often: a studio owner carries general liability and assumes they're covered when a client sues over a training-related injury. They're not. That claim falls squarely under professional liability, and without it, you're paying out of pocket for legal defense alone, which frequently ranges from $10,000 to $75,000 depending on the complexity of the injury. https://www.insureon.com/sports-fitness-business-insurance/personal-trainers/cost
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
What Gym Insurance Costs in South Carolina
Cost is the question every owner asks first, and the honest answer is: it depends heavily on your specific operation. A 1,500-square-foot Pilates studio with two instructors pays dramatically less than a 10,000-square-foot CrossFit box with heavy free weights and 15 employees.
That said, here are the main factors driving your premiums:
- Facility size and location (coastal locations cost more due to storm risk)
- Number of employees and independent contractors
- Types of activities offered (martial arts and boxing carry higher rates than yoga)
- Claims history
- Annual revenue and membership count
- Whether you offer childcare services
The OBBBA's permanent extension of the Section 199A deduction, now increased to 23% for qualified business income, provides meaningful tax relief for gym owners structured as S-corps, LLCs, or sole proprietorships. That savings can offset a portion of your insurance costs, making 2026 a reasonable time to invest in broader coverage.
An independent agency like CSP Insurance Services can compare quotes across multiple carriers rather than giving you a single take-it-or-leave-it number. That comparison shopping matters: premiums for identical coverage can vary 30% or more between carriers.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Additional Protections for Growing Fitness Brands
Once your core policies are in place, two additional coverages deserve serious consideration, especially for South Carolina operations.
Cyber Liability for Member Data
If you store member credit card numbers, health questionnaires, or billing information digitally, and virtually every gym does, you're a target. Cyber liability insurance covers data breach notification costs, credit monitoring for affected members, legal defense, and regulatory fines. A single breach can be costly to remediate, even for a small studio.
South Carolina's recent legislative updates allow electronic notifications for contract renewals, which is convenient but also increases the volume of sensitive digital communications your business handles. More digital touchpoints mean more exposure.
Business Interruption for Coastal Storms
Business interruption insurance replaces lost income when a covered event forces you to close temporarily. For coastal South Carolina gyms, this is not optional: it's survival planning. A closure after a hurricane can result in significant lost revenue, and that's before repair costs. Business interruption coverage bridges that gap so you can keep paying rent and staff while you rebuild.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Common Questions About SC Gym Insurance
Do I need insurance if I only teach group classes outdoors? Yes. Outdoor classes actually increase your liability exposure because you don't control the environment. Uneven terrain, weather changes, and public space hazards all create risk. Your general and professional liability policies should explicitly cover off-premises instruction.
Are waivers enough to protect my gym from lawsuits? Waivers help, but they're not bulletproof in South Carolina. Courts here have upheld liability waivers in some fitness contexts, but they can be invalidated if they're poorly written, if gross negligence is involved, or if the injured party is a minor. Think of waivers as one layer of protection, not a substitute for insurance.
Does my landlord's insurance cover my equipment? No. Your landlord's policy covers the building structure. Your equipment, signage, inventory, and tenant improvements need their own commercial property policy. This is one of the most common misconceptions among new gym owners.
Can I bundle all my gym insurance into one policy? Many carriers offer a Business Owner's Policy (BOP) that bundles general liability and property insurance at a lower combined rate. Professional liability and workers' comp are typically separate policies. CSP Insurance Services can help you figure out which combination makes sense for your setup without overpaying for coverage you don't need.
What happens if an employee gets hurt and I don't have workers' comp? If you meet the four-employee threshold and don't carry workers' comp, you face fines from the state, personal liability for medical costs, and potential criminal penalties. It's one of the riskiest coverage gaps a gym owner can have.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
How South Carolina's Insurance Market Is Shifting in 2026
The state's insurance landscape is going through a notable period of adjustment. The South Carolina Department of Insurance issued a mandatory data call on June 1, 2026, requiring insurers to report a full decade of premium and claim data by August 31, 2026. The goal is to assess liability market stability, and the results could influence how carriers price commercial policies going forward.
For gym owners, this means the market may see more competitive pricing as regulators push for transparency. It also means now is a smart time to review your current policies: if your carrier has been quietly raising rates, the increased market scrutiny may give you better options elsewhere.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Tax and Regulatory Updates That Affect Your Coverage Decisions
The permanent 23% QBI deduction under the OBBBA is the biggest tax development for fitness business owners in years. If you're structured as a pass-through entity, that deduction directly reduces your taxable income and frees up cash for insurance premiums, equipment upgrades, or expansion.
On the regulatory side, the surety bond requirement for prepaid contracts remains firmly in place. If you sell six-month or annual memberships, you need that bond of up to $50,000 filed with the Department of Consumer Affairs. Letting it lapse can jeopardize your Certificate of Authority and your ability to operate legally.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Making the Right Choice for Your Facility
Getting insurance for your South Carolina gym right isn't about buying the most expensive package available. It's about understanding your specific risks: your location, your activities, your staff size, your contract structure: and building coverage that matches. A boutique barre studio in downtown Charleston has fundamentally different needs than a 24-hour gym in Greenville, and their policies should reflect that.
The biggest mistake I see fitness business owners make is treating insurance as a checkbox item rather than a strategic decision. The second biggest mistake is not reviewing their coverage annually as their business grows. Adding a new trainer, expanding your class schedule, or opening a second location all change your risk profile.
If you're unsure where your current coverage stands or you're opening a new facility, working with an independent agency gives you access to multiple carriers and an objective look at what you actually need. CSP Insurance Services has been helping South Carolina businesses find the right fit since 1939. You can request a quote and get a real conversation with someone who understands the local market: no call centers, no chatbots, just straightforward guidance tailored to your gym.
About the author
Lawson Walker, CIC
I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.
As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.
Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Most Requested
Core business coverage.
The policies most South Carolina businesses start with.
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Workers Compensation
Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
General Liability
Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.
Inland Marine
Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.
Business Owners (BOP)
A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Personal Insurance
Coverage for your home, vehicles, and family.
Protect what matters most with personal policies shopped across our carriers.
Home
Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.
Auto
South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.
Umbrella
When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.
Boat
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Condo
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Industries We Serve
Specialized coverage for your industry.
Every industry carries its own risk. We help South Carolina businesses protect what they've built.
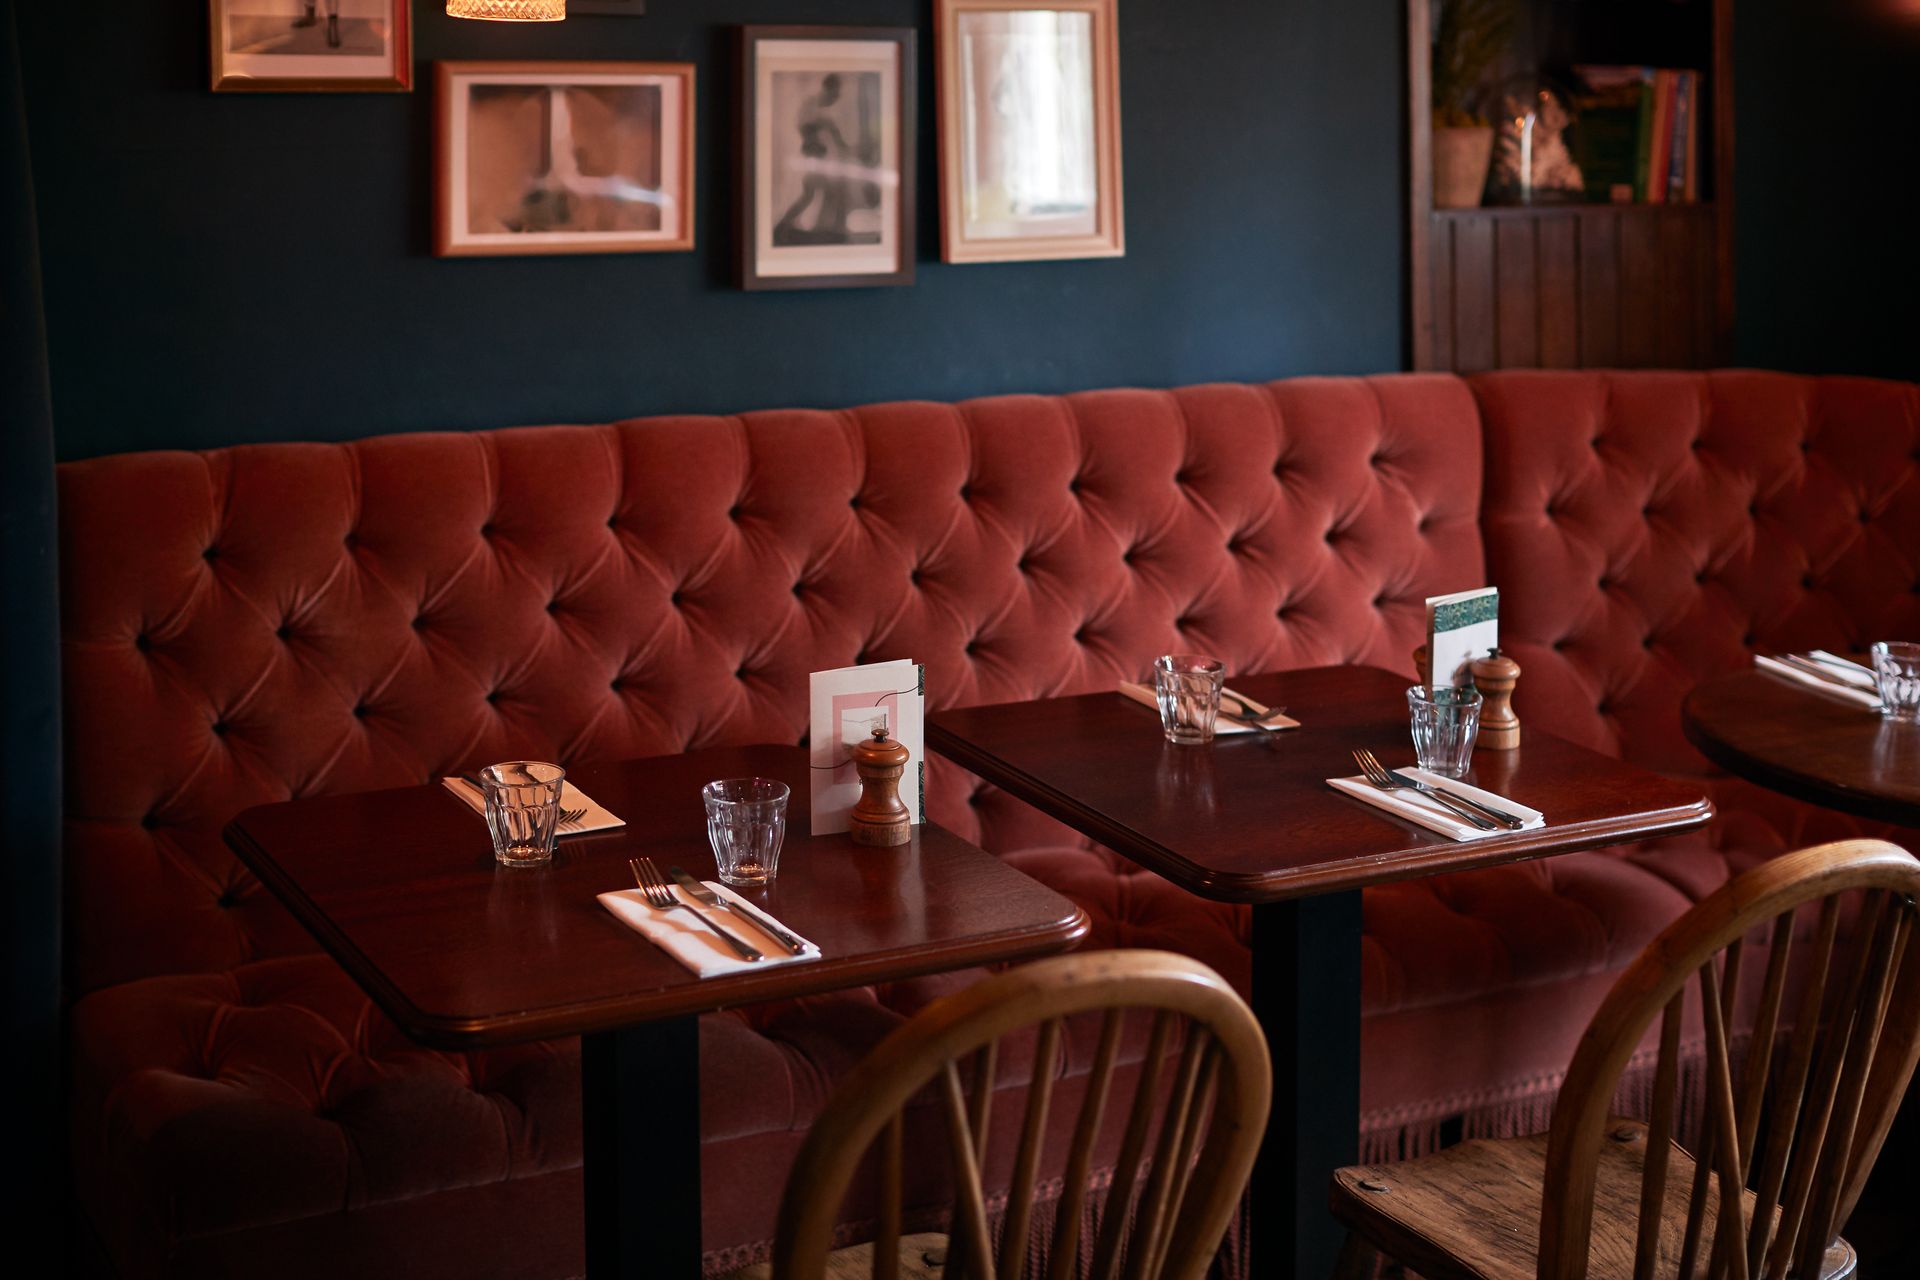
Restaurants
Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.
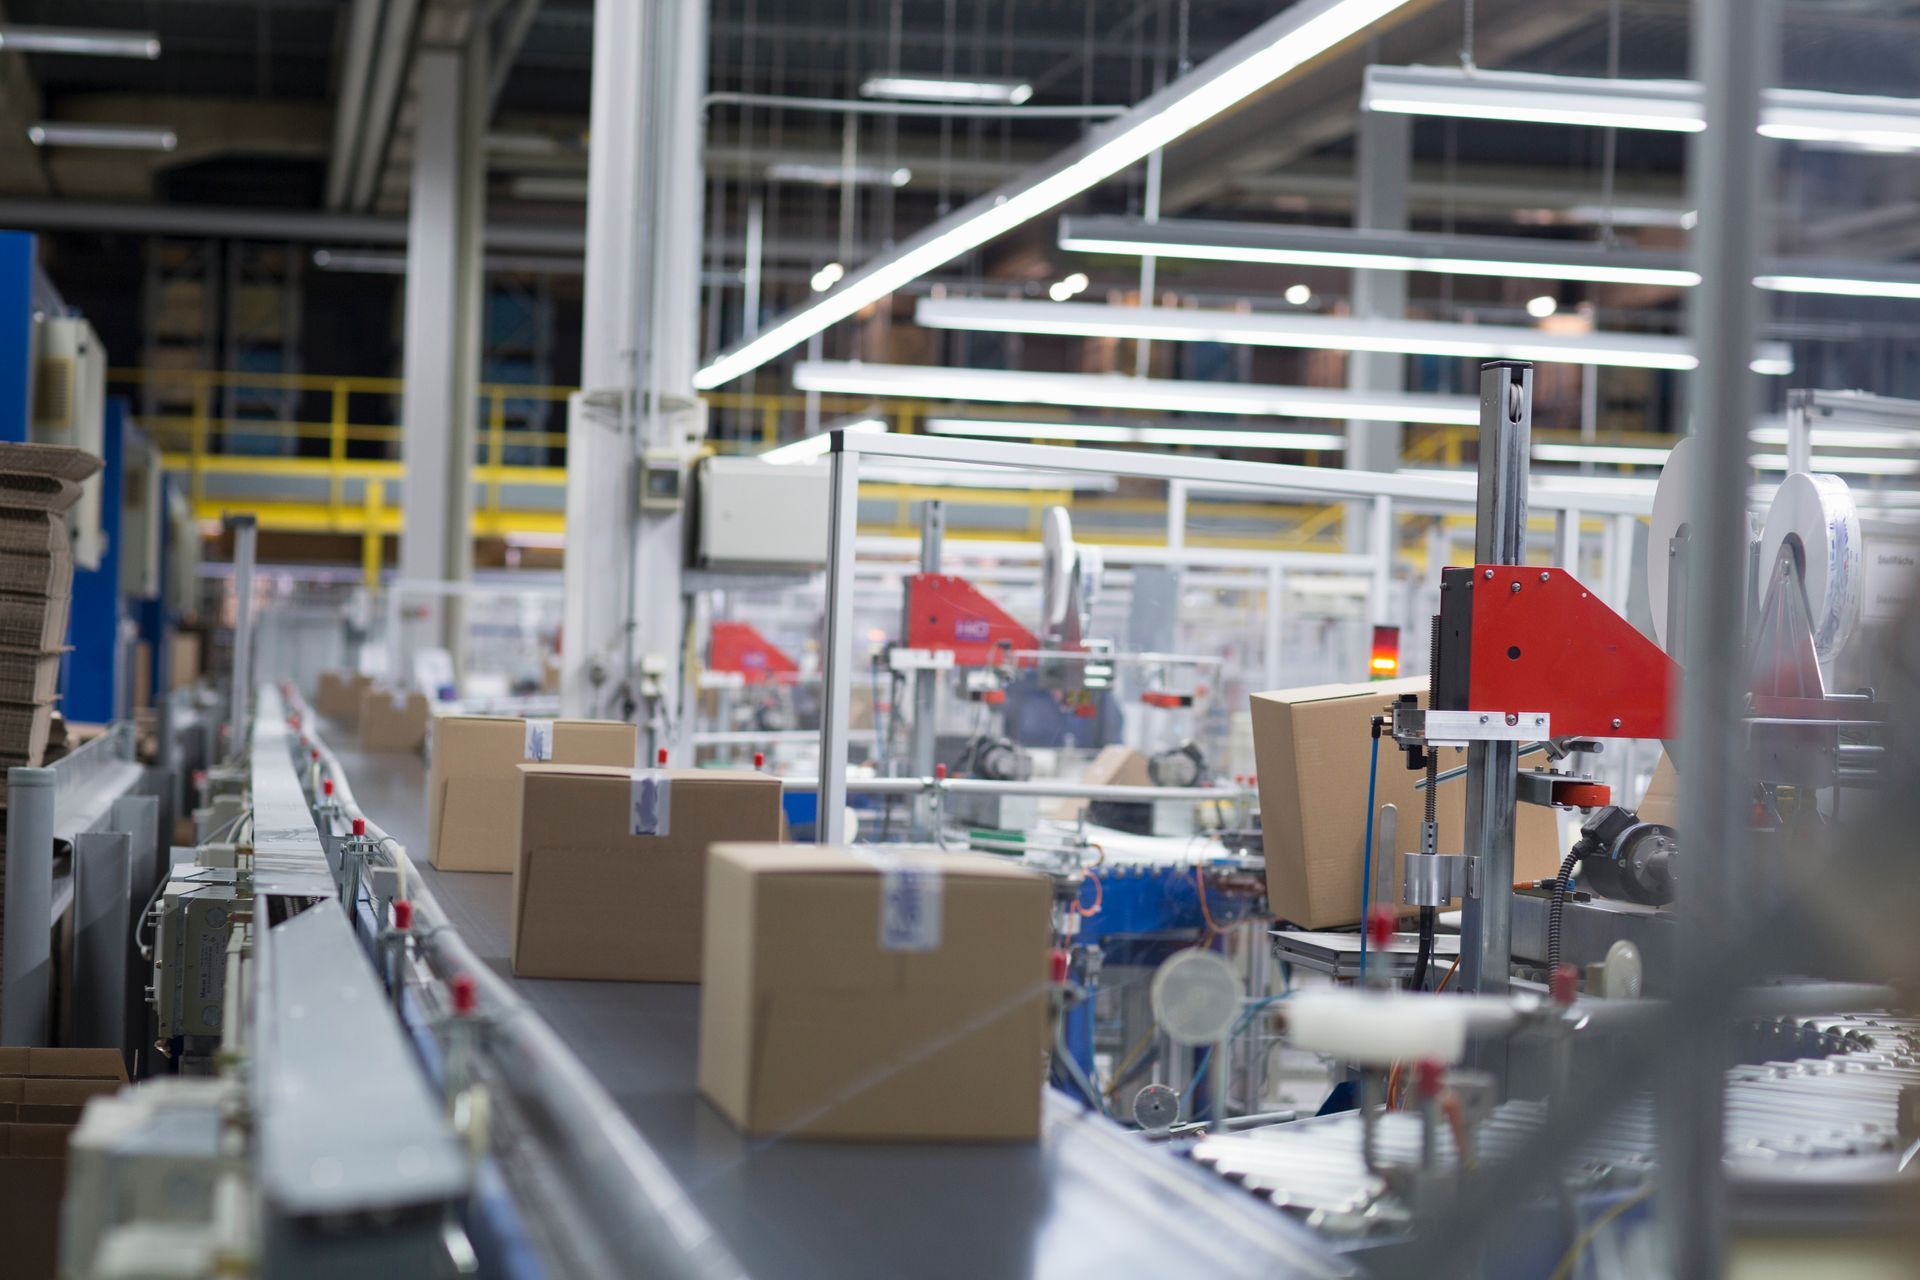
Manufacturers
From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.
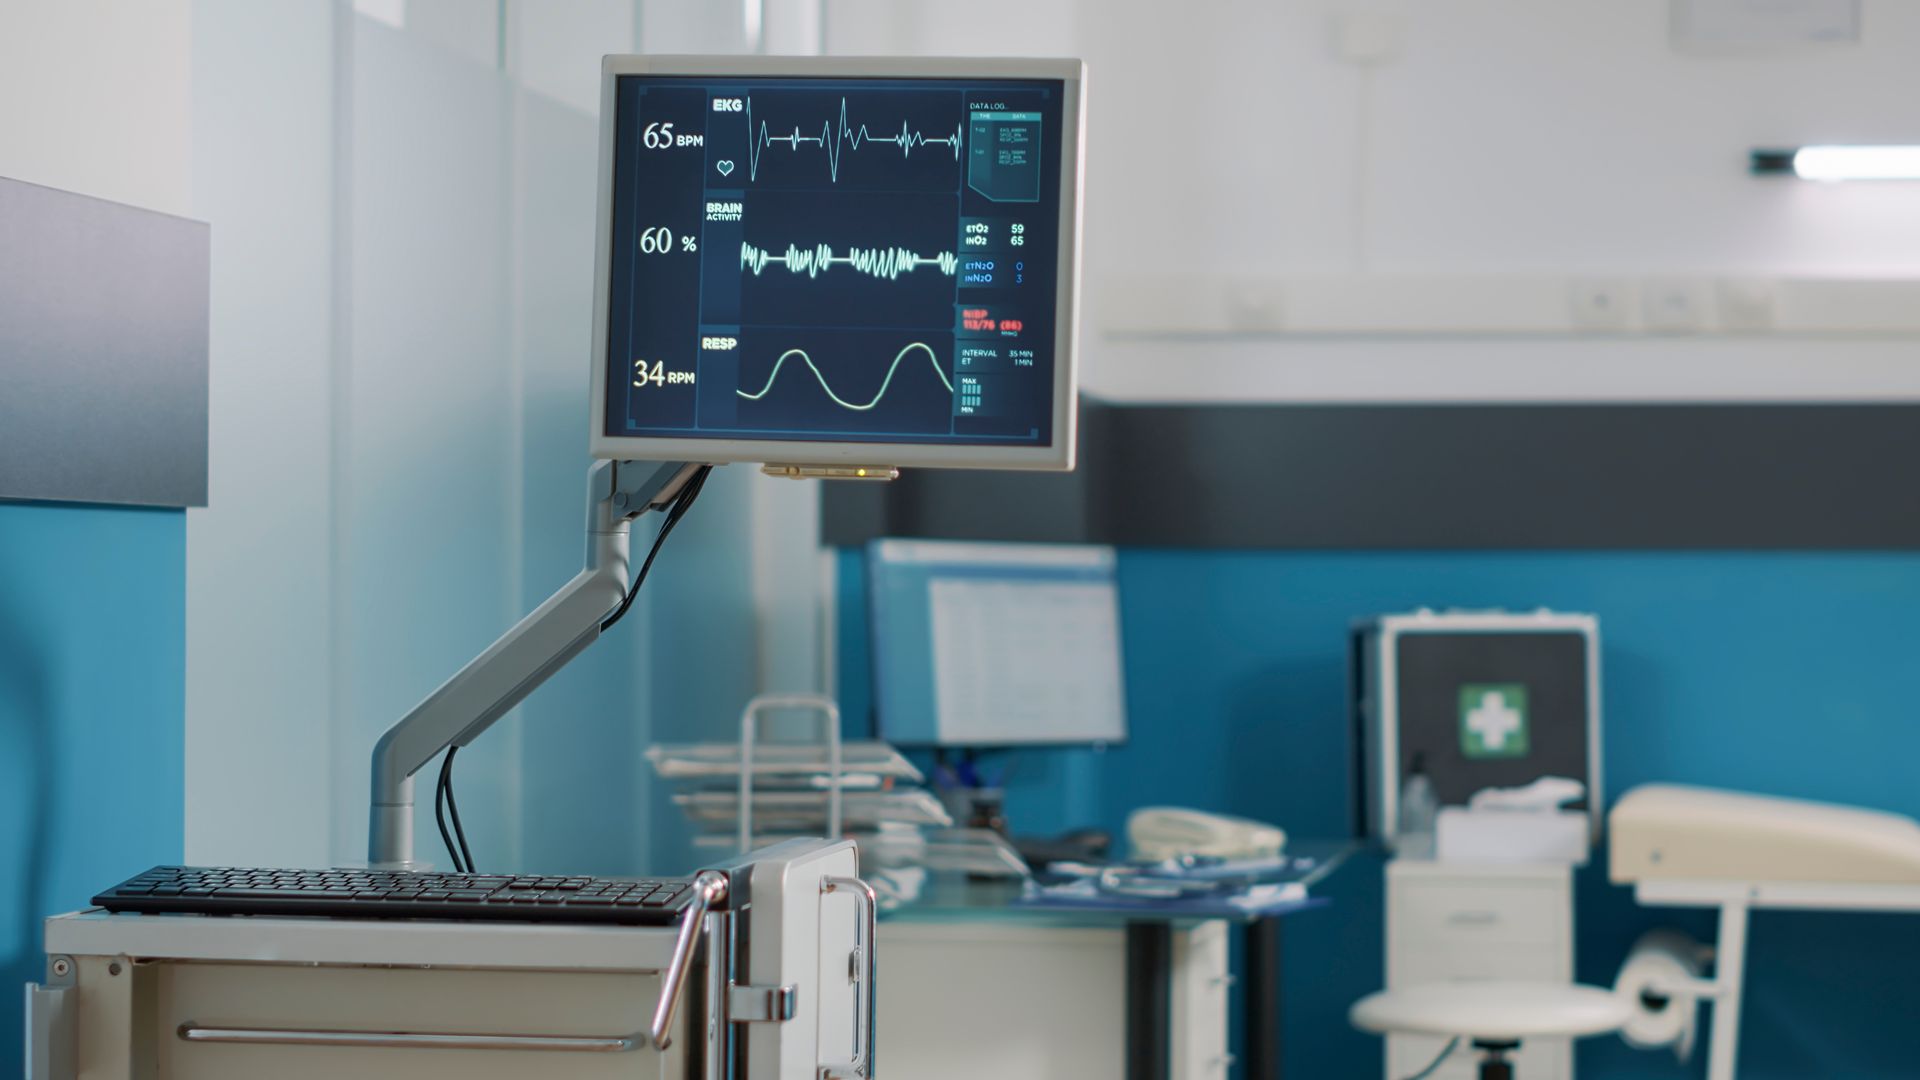
Healthcare Providers
Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
How It Works
Getting covered is simple.
Four steps, one real person from start to finish.
We compare carriers
We shop options across our carriers to find strong protection at a fair price.
We compare several carriers to find a policy that fits you, not one company's products.
Multi-carrier choice
Claims advocacy
When a claim happens, we stand in your corner and help move it forward with your carrier.
Local SC roots
We live and work in Florence and understand the risks your community faces because we face them too.
Client Reviews
Why clients choose CSP.
Independent advice, real people, and decades of local roots.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
FAQs
Questions, answered.
Straight answers about working with an independent agency.
What does an independent insurance agency do?
An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.
Do you cover both personal and business insurance?
Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.
How long has CSP been in business?
CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.
Will I work with a real person?
Always. No call centers and no chatbots — you work with a local team member who knows your account.
Which areas do you serve?
We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.
How do I get a quote?
Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.
How It Works
Insurance tips & updates.
Plain-language guidance to help you make confident decisions.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Get a Quote
Let's find your coverage.
Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.
2420 Hoffmeyer Road, Suite D
Florence, SC 29501
Mon–Fri 8:30am – 5:00pm