
South Carolina Business Flood Insurance

Five-star CSP Insurance Services reviews for South Carolina Large Group Health Insurance

CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance icon

Hospital bills, treatment, and prescriptions for a work-related injury or illness.

Medical expenses

Claims history

Feature Short-Term Disability Long-Term Disability
Waiting Period 7-14 days 90-180 days
Benefit Duration Up to 26 weeks 2 years to age 65+
Income Replacement 60%-70% 50%-60%
Common Claims Surgery recovery, pregnancy, fractures Cancer, heart disease, chronic conditions
Typical Cost $0.10-$0.50 per $100 of payroll $0.20-$0.60 per $100 of payroll
Best For Bridging short absences Protecting against career-ending events
General Liability Professional Liability
What it covers Bodily injury, property damage, personal injury on premises Errors in care, negligent supervision, failure to follow care plans
Example claim Visitor slips on wet floor Staff administers wrong medication dosage
Typical limits $1M per occurrence / $2M aggregate $1M per occurrence / $3M aggregate
Average cost ~$91/month for social service providers $100-$200/month depending on services
Who files claims Visitors, vendors, third parties Residents, families, guardians

General liability insurance for social service organizations currently averages about $91 per month for a $1M/$2M policy. Professional liability typically runs higher because the claims tend to be more complex and costly. Skipping either one is a mistake I've seen operators make, usually because they assume one policy covers everything.

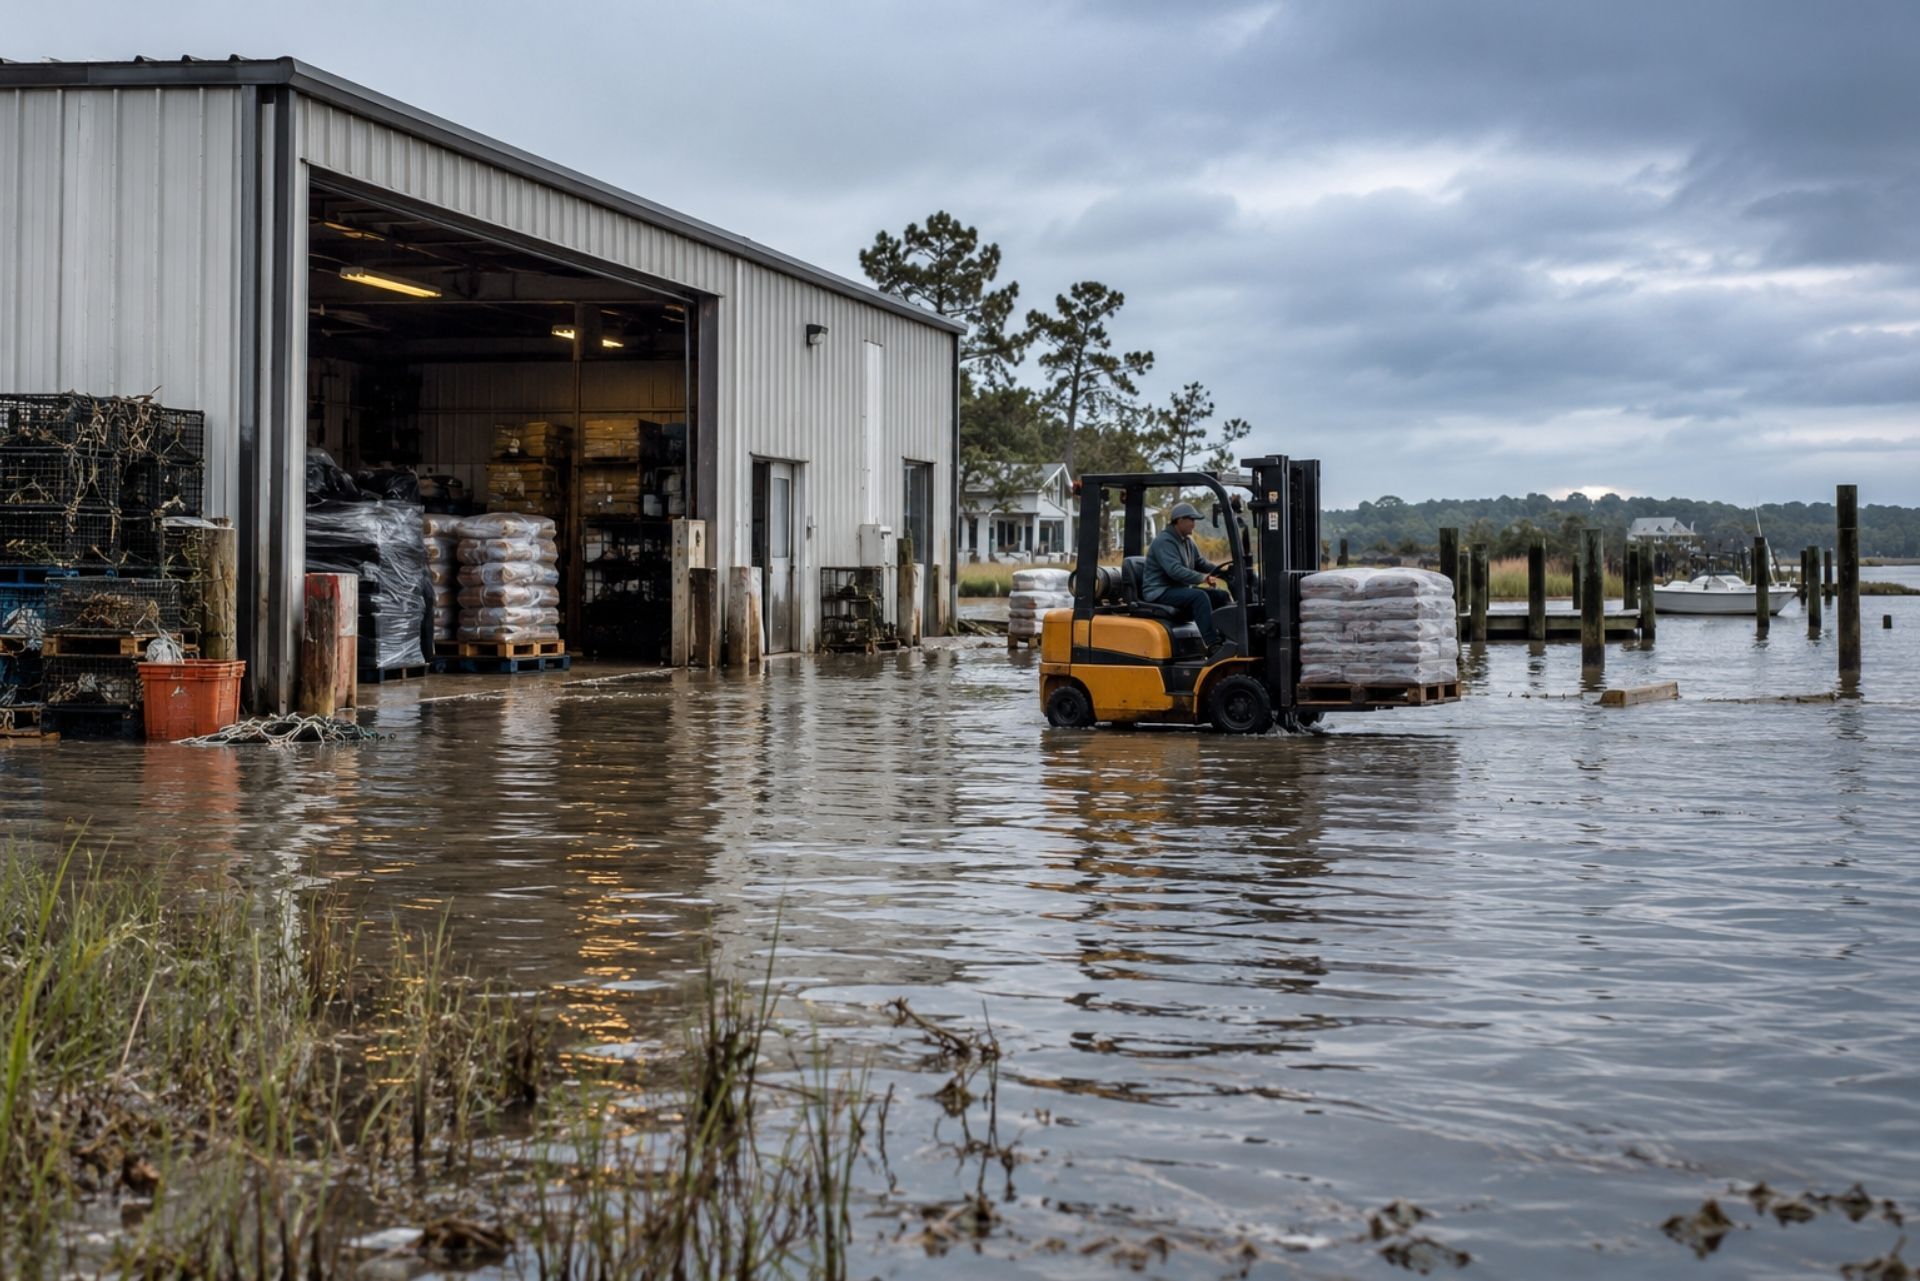
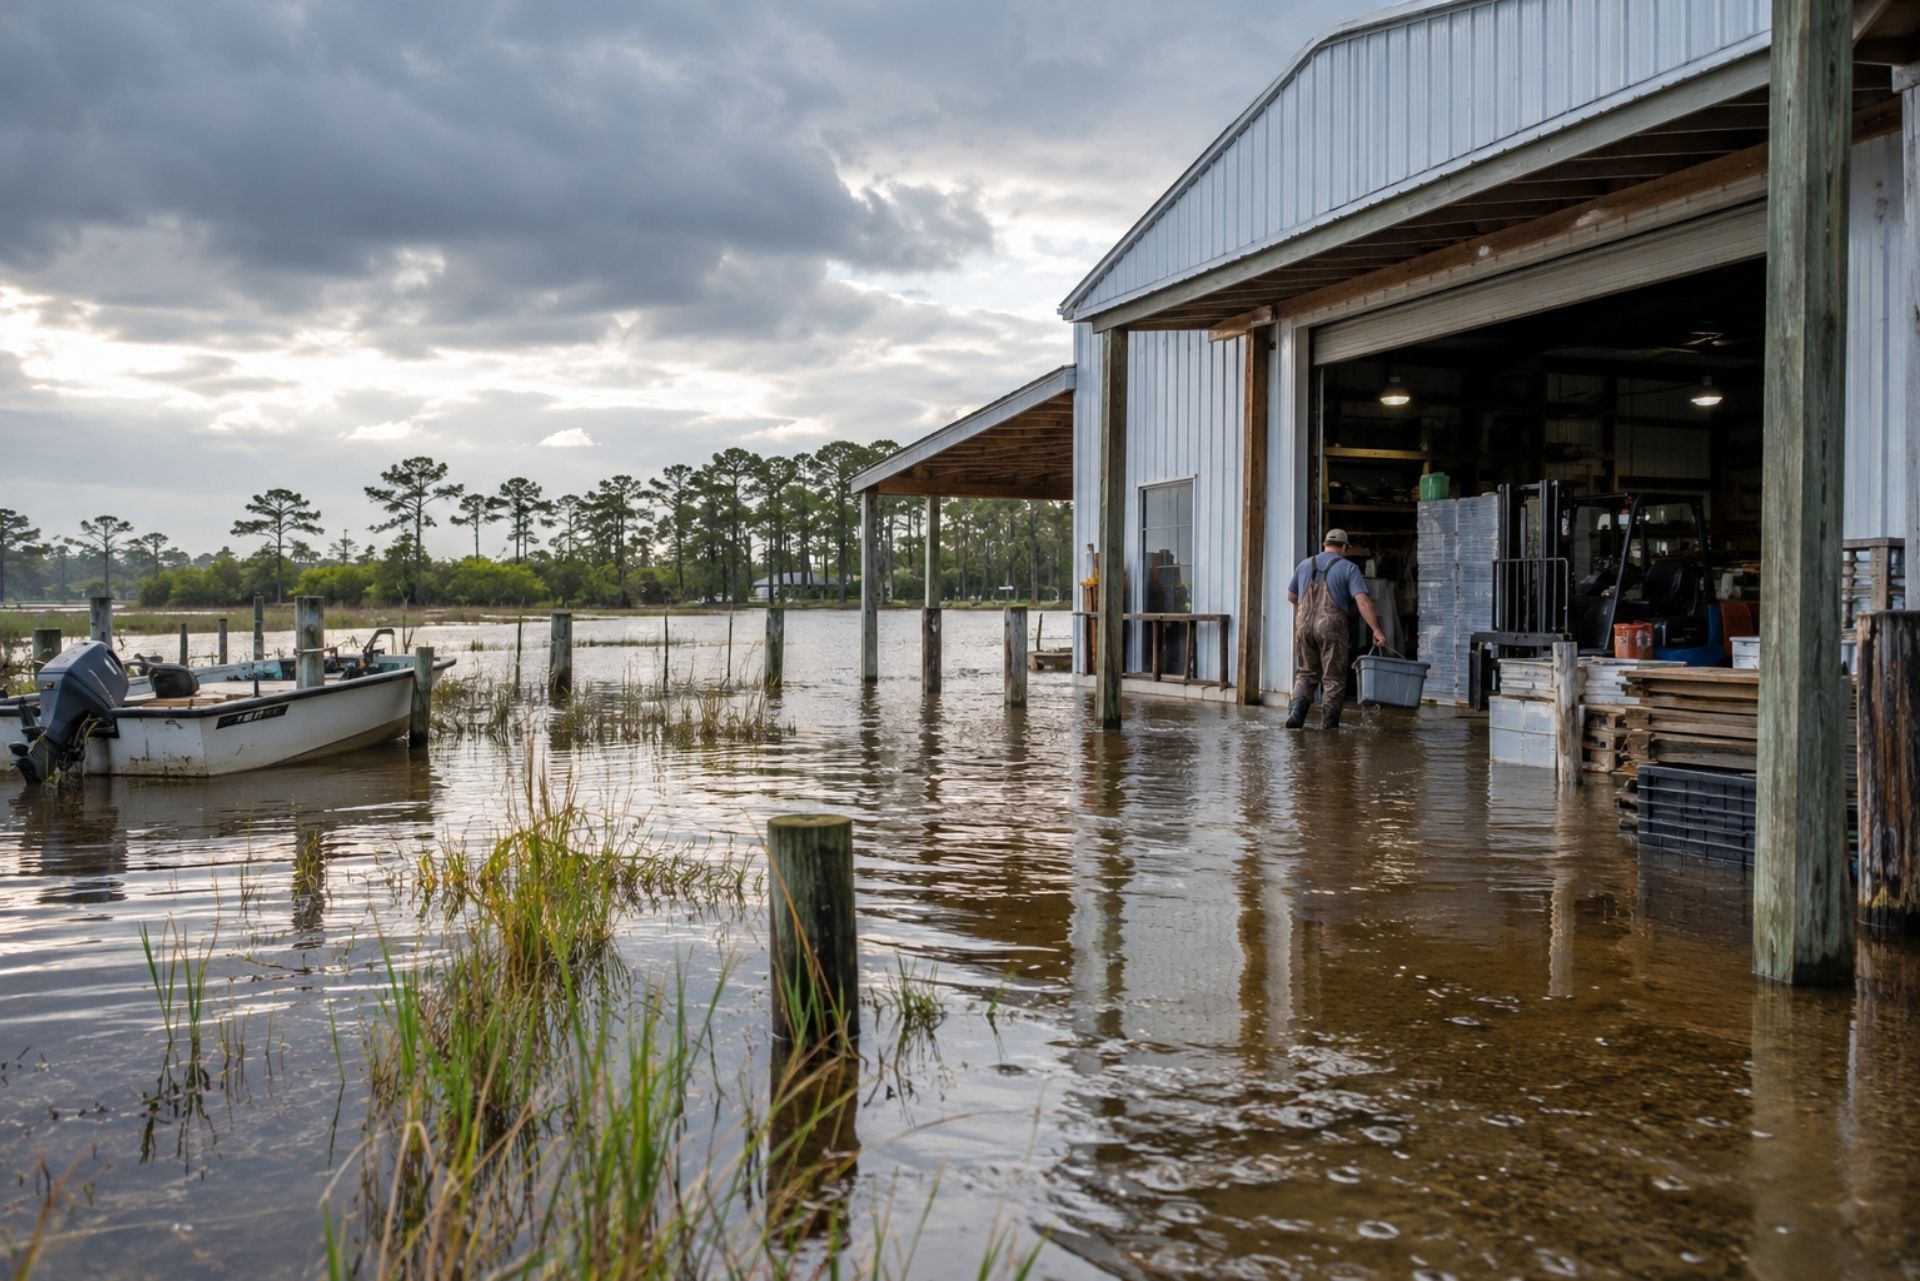
Picture a restaurant on Highway 17 in Myrtle Beach after a tropical storm pushes two feet of water through the dining room. The owner calls the agent, confident the commercial policy will handle it, and learns the claim is denied. That conversation happens every hurricane season in South Carolina. The reason has little to do with bad luck and a lot to do with how commercial policies are written. This guide covers why your property policy stops short, how NFIP and private coverage differ, and what limits and costs look like for SC businesses in 2026. Whether you run a medical practice in Florence, a manufacturing plant in Rock Hill, or a nonprofit in Columbia, flood risk does not respect FEMA map lines. Roughly a quarter of flood claims nationally come from outside high-risk zones, and inland rivers like the Congaree and Pee Dee have proven that point repeatedly.

Why Standard Commercial Property Policies Leave SC Businesses At Risk

Here's the hard truth: standard commercial policies, including Commercial Package Policies and Business Owners Policies, universally exclude coverage for flood damage. The South Carolina Department of Insurance spells it out plainly: water from street flooding, an overflowing creek or river, or storm surge is generally only covered by a separate flood policy.


Business owners often blur wind and water. Your property policy may pay when hurricane winds tear off a roof and rain pours in. When the same storm pushes surge into your warehouse, that's "rising water," and it's excluded. Adjusters spend real time separating wind damage from flood damage on coastal claims, and the split decides who pays.


The stakes are steep. Only 40% of businesses without dedicated flood coverage reopen after a flood. One attorney who reviews Carolina storm claims put it well: the coverage in place was narrower than its owner believed, and the gap became visible only when it was too late to close it.

South Carolina Large Group Health Insurance quote with CSP Insurance Services
Lawson Walker F of CSP Insurance Services, helping with South Carolina Large Group Health Insurance

Your CSP agent

Lawson Walker, CIC

Insurance Sales

CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.

From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.

Fine Arts and High-Value Specialized Goods

Galleries, auction houses, and even corporate offices with art collections need specialized coverage. Standard property policies cap fine art at absurdly low limits, sometimes $2,500 per item. A fine arts floater provides agreed-value coverage, meaning you and the insurer agree on the item's worth upfront. If it's damaged or stolen, that's what you get paid.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Feature Admitted (Standard) Carriers Non-Admitted (E&S) Carriers
State regulation Fully regulated; rates filed with state Exempt from rate filing; flexible pricing
Guaranty fund protection Yes: state fund covers claims if carrier fails No: no guaranty fund backstop
Policy forms Standardized (ISO forms common) Manuscript or custom forms
Risk appetite Prefers low-to-moderate risk Accepts high-risk and unusual exposures
Premium cost Generally lower Typically 20-75% higher
Surplus lines tax Not applicable Buyer pays state surplus lines tax (varies 2-5%)
Speed of placement Standard timelines Can be faster or slower depending on complexity

Computer Equipment and Data Storage

Blog Workers Comp from CSP Insurance Services

Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.
Comparing NFIP and Private Flood Insurance Options

Your two main paths are the federal program and the private market. Each has a place, and plenty of South Carolina businesses end up using both.

The National Flood Insurance Program (NFIP) Framework

The NFIP, run by FEMA, has been the default option for decades. It offers standardized forms, predictable pricing, and availability in participating communities regardless of a carrier's appetite for risk. In October 2026, FEMA launched a digital self-service tool for South Carolinians to view options, get quotes, and buy coverage online.


The catch is structural. The program is running on a short-term extension, and Congress must act to keep its authority to issue new contracts from expiring on December 11, 2026. Lapses have happened before, stalling new policies and some real estate closings.

Advantages of the Private Flood Market

Private carriers have grown fast. They now hold 48% of the U.S. commercial flood market, up from 23% in 2018. That growth reflects real advantages: higher limits, shorter or no waiting periods on some forms, and options like business income coverage, which the NFIP doesn't offer for commercial properties.


Private policies vary widely, though. Some carriers exclude basements or cap certain contents, so the fine print matters more here than with the standardized federal form.

Comparison Table: NFIP vs. Private Commercial Flood

Feature NFIP Private Market
Building limit $500,000 max Up to $50 million
Contents limit $500,000 max Up to $10 million
Waiting period 30 days standard Often shorter, varies
Business income Not included Available on many forms
Policy terms Standardized Varies by carrier
Program stability Subject to reauthorization Not tied to Congress
South Carolina Large Group Health Insurance

Factors That Influence Your Premium Costs

Several variables drive what you'll pay:


  • Specialty: Neurosurgeons pay far more than internists
  • Claims history: Prior claims increase your rates, sometimes dramatically
  • Location: Urban areas with higher jury awards tend to cost more
  • Policy type: Occurrence policies cost more than claims-made
  • Coverage limits: Higher limits mean higher premiums
  • Years in practice: New physicians sometimes pay less initially on claims-made policies (the "step" or "mature" rate system)


The trend line isn't encouraging. Malpractice claims data for 2026 shows continued growth in both claim frequency and severity, meaning premiums are likely to keep rising. Shopping your coverage through an independent agency that compares multiple carriers can save you thousands annually without sacrificing protection.

For most commercial projects, extended coverage with appropriate endorsements is the smarter choice. The premium difference is often modest compared to the potential gap in coverage.

Understanding Coverage Limits and Cost Drivers in South Carolina

The NFIP caps commercial coverage at $500,000 for the building and $500,000 for contents. That sounds generous until you price out a Charleston-area medical office with imaging equipment or a Florence manufacturer with specialized machinery. For many commercial properties, $500,000 doesn't rebuild the structure, let alone replace inventory. Private carriers can write up to $50 million on buildings and $10 million on contents.


A common workaround is layering: an NFIP primary policy with private "excess" flood coverage above it. This keeps the federal base while closing the gap on higher-value properties.


As of late 2026, typical annual flood premiums in South Carolina run about $1,093 for NFIP policies and $1,104 for private options. Treat those as averages, not quotes. Your actual cost depends on:


  • Flood zone and elevation relative to base flood elevation
  • Building construction, foundation type, and age
  • Distance to water, whether the Atlantic, Waccamaw, or a local creek
  • Limits and deductibles you select
  • Mitigation steps like flood vents or elevated equipment


Timing also matters. The NFIP's standard 30-day waiting period means buying when a storm is already in the Gulf usually comes too late.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Boat and Watercraft Coverage for Weekend Adventures

Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.


Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.

Feature Admitted (Standard) Carriers Non-Admitted (E&S) Carriers
State regulation Fully regulated; rates filed with state Exempt from rate filing; flexible pricing
Guaranty fund protection Yes: state fund covers claims if carrier fails No: no guaranty fund backstop
Policy forms Standardized (ISO forms common) Manuscript or custom forms
Risk appetite Prefers low-to-moderate risk Accepts high-risk and unusual exposures
Premium cost Generally lower Typically 20-75% higher
Surplus lines tax Not applicable Buyer pays state surplus lines tax (varies 2-5%)
Speed of placement Standard timelines Can be faster or slower depending on complexity

This is a policy feature that doesn't get enough attention. A consent-to-settle clause gives you the right to approve or reject any settlement offer your insurer wants to make. Without it, your carrier can settle a claim you believe is meritless, and that settlement goes on your record.


Some policies include a "hammer clause" instead: if you refuse a settlement the insurer recommends and the case goes to trial with a worse outcome, you're responsible for the difference. Understanding this clause before you buy a policy is critical. At CSP Insurance Services, their team walks clients through these policy details line by line, which matters because the fine print in malpractice policies can have career-altering consequences.

The Role of Consent-to-Settle Clauses

Errors and Omissions (E&O) for Design Flaws

If your shop does any design work, engineering consultation, or CAD/CAM programming for clients, E&O insurance is essential. This covers claims where your professional judgment or technical expertise leads to a client's financial loss.


A common scenario: your shop designs a custom fixture based on a client's rough specifications, the fixture fails during production, and the client claims your design was flawed. Without E&O coverage, you're defending that claim and paying any settlement from your own funds. Product recall insurance trends in 2026 show that insurers are paying closer attention to design-related exposures, which means getting E&O in place now is smarter than waiting until underwriting tightens further.

Common Questions About South Carolina Business Flood Insurance

Do I need flood insurance if I'm not in a high-risk zone? Lenders only require it in high-risk zones, but floods routinely hit moderate and low-risk areas. Coverage outside high-risk zones often costs less, which makes it an easy decision.


Does my BOP cover hurricane damage? It typically covers wind damage, subject to a named-storm or hurricane deductible. Storm surge and rising water require a separate flood policy.


Can I buy flood coverage right before a hurricane? You can buy it, but NFIP policies usually take 30 days to activate. Some private policies start sooner, but many carriers stop writing in an area once a storm is named.


Does flood insurance cover lost income while I'm closed? NFIP commercial policies don't. Many private flood policies offer business income coverage as an option.


Is private flood insurance accepted by my lender? Most lenders accept private flood policies that meet federal requirements. Confirm with your lender before switching.


What happens if the NFIP lapses? Existing policies generally stay in force, but new policies and renewals can stall until Congress acts.

Specialty Lines: Flood, Earthquake, and Valuable Items

Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.


Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.


Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.

FAQ: What counts as a disability? Does it cover mental health? Are benefits taxable?

What qualifies as a disability under most group plans? Most policies define disability as the inability to perform the essential duties of your own occupation (for the first 1-2 years) and later shift to an "any occupation" standard. The exact definition varies by carrier and policy, so reading the contract language matters.


Does disability insurance cover mental health conditions? Yes, most modern group disability policies cover mental health conditions like depression, anxiety, and PTSD. However, many policies limit mental health claims to 24 months of benefits, even if the overall policy pays to age 65. Ask about this limitation before you buy.


Are disability benefits taxable? It depends on who pays the premium. If the employer pays, benefits are taxable to the employee. If the employee pays with after-tax dollars, benefits are received tax-free.


Can employees receive both workers' comp and disability benefits? Generally, no. Most disability policies include an offset provision that reduces benefits by the amount of workers' compensation received. The two programs are designed to complement each other, not stack.


Is there a waiting period before new employees can enroll? Most group plans allow employers to set an eligibility waiting period, commonly 30, 60, or 90 days. South Carolina doesn't regulate this waiting period for disability coverage, so it's up to the employer.


What happens if an employee is partially disabled? Many LTD policies include a partial or residual disability benefit that pays a reduced amount if the employee can work part-time but not full-time. This feature encourages return-to-work efforts while still providing financial support.

Factors That Influence Your Monthly Premiums

Several factors drive your builders risk premium. Project type matters: a wood-frame apartment complex costs more to insure than a concrete tilt-up warehouse. Location is significant, especially in South Carolina where coastal proximity affects wind/hail rates dramatically. A project in Florence will price very differently from one on the Grand Strand.


Other factors include project duration, the contractor's loss history, protective safeguards on-site (fencing, security cameras, fire extinguishers), and the deductible you choose. Premiums typically run between 1% and 4% of the total project value, though market conditions in early 2026 have pushed rates toward the lower end for well-managed projects.

Usually, yes. A single claim can increase your premiums by 10% to 30% or more, depending on the severity and outcome. Some carriers offer claims-free discounts that you'd lose. That said, a claim that's dismissed or results in no payout has less impact than one with a large settlement. Shopping your renewal through an independent agent can help offset rate increases by comparing offers from competing carriers.

FAQ: Will my rates go up if I have one claim?

Apartment complex insurance isn't a single policy: it's a coordinated set of coverages that work together to protect your buildings, your income, your employees, and your financial future. The right package includes general liability, commercial property, workers comp, commercial auto, and specialized add-ons like loss of rental income and equipment breakdown. Skipping any one of these creates a gap that a single bad claim can exploit.


The most effective approach is working with an independent agency that can compare options across multiple carriers. CSP Insurance Services has been helping South Carolina property owners build customized coverage programs since 1939, with direct access to real people who understand multifamily risk. If you're unsure whether your current coverage matches your actual exposure, or if you're purchasing a new complex and need to build a policy from scratch, request a quote to get a personalized analysis of your insurance needs. A 20-minute conversation now can save you six figures when a claim hits.

Does general liability cover fuel spills?

Usually not. Most GL policies contain pollution exclusions that specifically exclude fuel spills and environmental contamination. You need a separate pollution liability policy to cover cleanup costs, third-party damages, and regulatory fines from fuel releases.

Making the Right Choice for Your Coastal or Inland Property

There's no single right answer, and that's the point. A small retail shop in an inland Columbia strip center might be well served by a basic NFIP policy. A beachfront hotel in North Myrtle Beach likely needs private limits or a layered program. A Rock Hill nonprofit leasing space should focus on contents and improvements, since the landlord's policy won't cover them.


The biggest mistakes come from assumptions: assuming the property policy covers water, assuming $500,000 is plenty, or assuming you can buy coverage when the forecast turns. Each costs businesses real money after a storm.


Flood protection is one of the few coverage decisions where a wrong guess can end a business, so it pays to compare. As an independent agency serving South Carolina since 1939, CSP Insurance Services can review NFIP and private options side by side and match limits to your actual exposure. If you'd like to see where you stand before the next storm season, request a flood quote and talk with a real person who knows these policies inside out.

About the author

Lawson Walker, CIC

I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.


As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.


Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience
South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Meet Richard

Most Requested

Core business coverage.

The policies most South Carolina businesses start with.

Commercial Property Insurance from CSP Insurance Services

Commercial Property

Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Workers Comp from CSP Insurance Services

Workers Compensation

Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.

Commercial Auto Insurance from CSP Insurance Services

Commercial Auto

Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

General Liability from CSP Insurance Services

General Liability

Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.

Inland Marine Insurance from CSP Insurance Services

Inland Marine

Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.

Business Owners Policy from CSP Insurance Services

Business Owners (BOP)

A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Lawson of CSP Insurance Services, helping with South Carolina Large Group Health Insurance

Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Personal Insurance

Coverage for your home, vehicles, and family.

Protect what matters most with personal policies shopped across our carriers.

South Carolina Large Group Health Insurance icon

Home

Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.

South Carolina Large Group Health Insurance icon

Auto

South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.

South Carolina Large Group Health Insurance icon

Umbrella

When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.

South Carolina Large Group Health Insurance icon

Boat

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

South Carolina Large Group Health Insurance icon

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
South Carolina Large Group Health Insurance icon

Condo

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Lawson of CSP Insurance Services, helping with South Carolina Large Group Health Insurance

Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

South Carolina Large Group Health Insurance icon
Get a Quote
South Carolina Large Group Health Insurance icon

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
South Carolina Large Group Health Insurance icon
Get a Quote

Industries We Serve

Specialized coverage for your industry.

Every industry carries its own risk. We help South Carolina businesses protect what they've built.

Restaurant Insurance from CSP Insurance Services

Restaurants

Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.

Manufacturer Insurance from CSP Insurance Services

Manufacturers

From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.

Healthcare Insurance from CSP Insurance Services

Healthcare Providers

Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Commercial Property Insurance from CSP Insurance Services

Commercial Property

Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Meet Richard View all business coverage Get a Quote

Commercial Auto

Get a Quote

Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

How It Works

Getting covered is simple.

Four steps, one real person from start to finish.

Tell us about you

Share a few details about what you need to protect. A real person reviews it.

We compare carriers

We shop options across our carriers to find strong protection at a fair price.

We recommend coverage

We walk you through the policy in plain language and answer every question.

You get covered

Sign with confidence — and we stay on for changes, claims, and yearly reviews.

We compare several carriers to find a policy that fits you, not one company's products.

Multi-carrier choice

South Carolina Large Group Health Insurance icon

Claims advocacy

When a claim happens, we stand in your corner and help move it forward with your carrier.

South Carolina Large Group Health Insurance icon

Local SC roots

We live and work in Florence and understand the risks your community faces because we face them too.

Client Reviews

Why clients choose CSP.

Independent advice, real people, and decades of local roots.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Lawson of CSP Insurance Services, helping with South Carolina Large Group Health Insurance

Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

South Carolina Large Group Health Insurance icon
Get a Quote
South Carolina Large Group Health Insurance icon

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
South Carolina Large Group Health Insurance icon
Get a Quote

FAQs

Questions, answered.

Straight answers about working with an independent agency.

South Carolina Large Group Health Insurance - Sc Statehouse
  • What does an independent insurance agency do?

    An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.

  • Do you cover both personal and business insurance?

    Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.

  • How long has CSP been in business?

    CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.

  • Will I work with a real person?

    Always. No call centers and no chatbots — you work with a local team member who knows your account.

  • Which areas do you serve?

    We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.

  • How do I get a quote?

    Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.

How It Works

Insurance tips & updates.

Plain-language guidance to help you make confident decisions.

Commercial Auto Versus Personal Auto for Business Use in South Carolina: Covered Vehicles, Employee
3 November 2026
Compare personal vs. commercial auto insurance in South Carolina with CSP Insurance Services. Protect business vehicles, drivers, and assets.
Workers' Comp Ghost Policies in South Carolina: What They Are and Who Needs One
3 November 2026
Learn about South Carolina workers' comp ghost policies, costs, and requirements with CSP Insurance Services.
How South Carolina Small Businesses Can Lower Their Insurance Premiums: Class Codes, Deductibles, Sa
3 November 2026
Lower your South Carolina business insurance costs with CSP Insurance Services. Explore class codes, safety programs, bundling, and premium savings.

We compare several carriers to find a policy that fits you, not one company's products.

◆

80+ years local experience

South Carolina Large Group Health Insurance - Florence Statue

1939

Serving SC

Lawson of CSP Insurance Services, helping with South Carolina Large Group Health Insurance

Insurance Sales

J. Roger Jordan, CIC

Meet Richard

[CONFIRM bio]

Get a Quote

Boat

Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.

Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.

Condo

South Carolina Large Group Health Insurance icon
Get a Quote
South Carolina Large Group Health Insurance icon

Motorcycle

Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
South Carolina Large Group Health Insurance icon
Get a Quote

Get a Quote

Let's find your coverage.

Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.

South Carolina Large Group Health Insurance icon

2420 Hoffmeyer Road, Suite D
Florence, SC 29501

South Carolina Large Group Health Insurance icon

Mon–Fri 8:30am – 5:00pm