
CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
Hospital bills, treatment, and prescriptions for a work-related injury or illness.
Medical expenses
Claims history
| Feature | Short-Term Disability | Long-Term Disability |
|---|---|---|
| Waiting Period | 7-14 days | 90-180 days |
| Benefit Duration | Up to 26 weeks | 2 years to age 65+ |
| Income Replacement | 60%-70% | 50%-60% |
| Common Claims | Surgery recovery, pregnancy, fractures | Cancer, heart disease, chronic conditions |
| Typical Cost | $0.10-$0.50 per $100 of payroll | $0.20-$0.60 per $100 of payroll |
| Best For | Bridging short absences | Protecting against career-ending events |
| General Liability | Professional Liability | |
|---|---|---|
| What it covers | Bodily injury, property damage, personal injury on premises | Errors in care, negligent supervision, failure to follow care plans |
| Example claim | Visitor slips on wet floor | Staff administers wrong medication dosage |
| Typical limits | $1M per occurrence / $2M aggregate | $1M per occurrence / $3M aggregate |
| Average cost | ~$91/month for social service providers | $100-$200/month depending on services |
| Who files claims | Visitors, vendors, third parties | Residents, families, guardians |
General liability insurance for social service organizations currently averages about $91 per month for a $1M/$2M policy. Professional liability typically runs higher because the claims tend to be more complex and costly. Skipping either one is a mistake I've seen operators make, usually because they assume one policy covers everything.
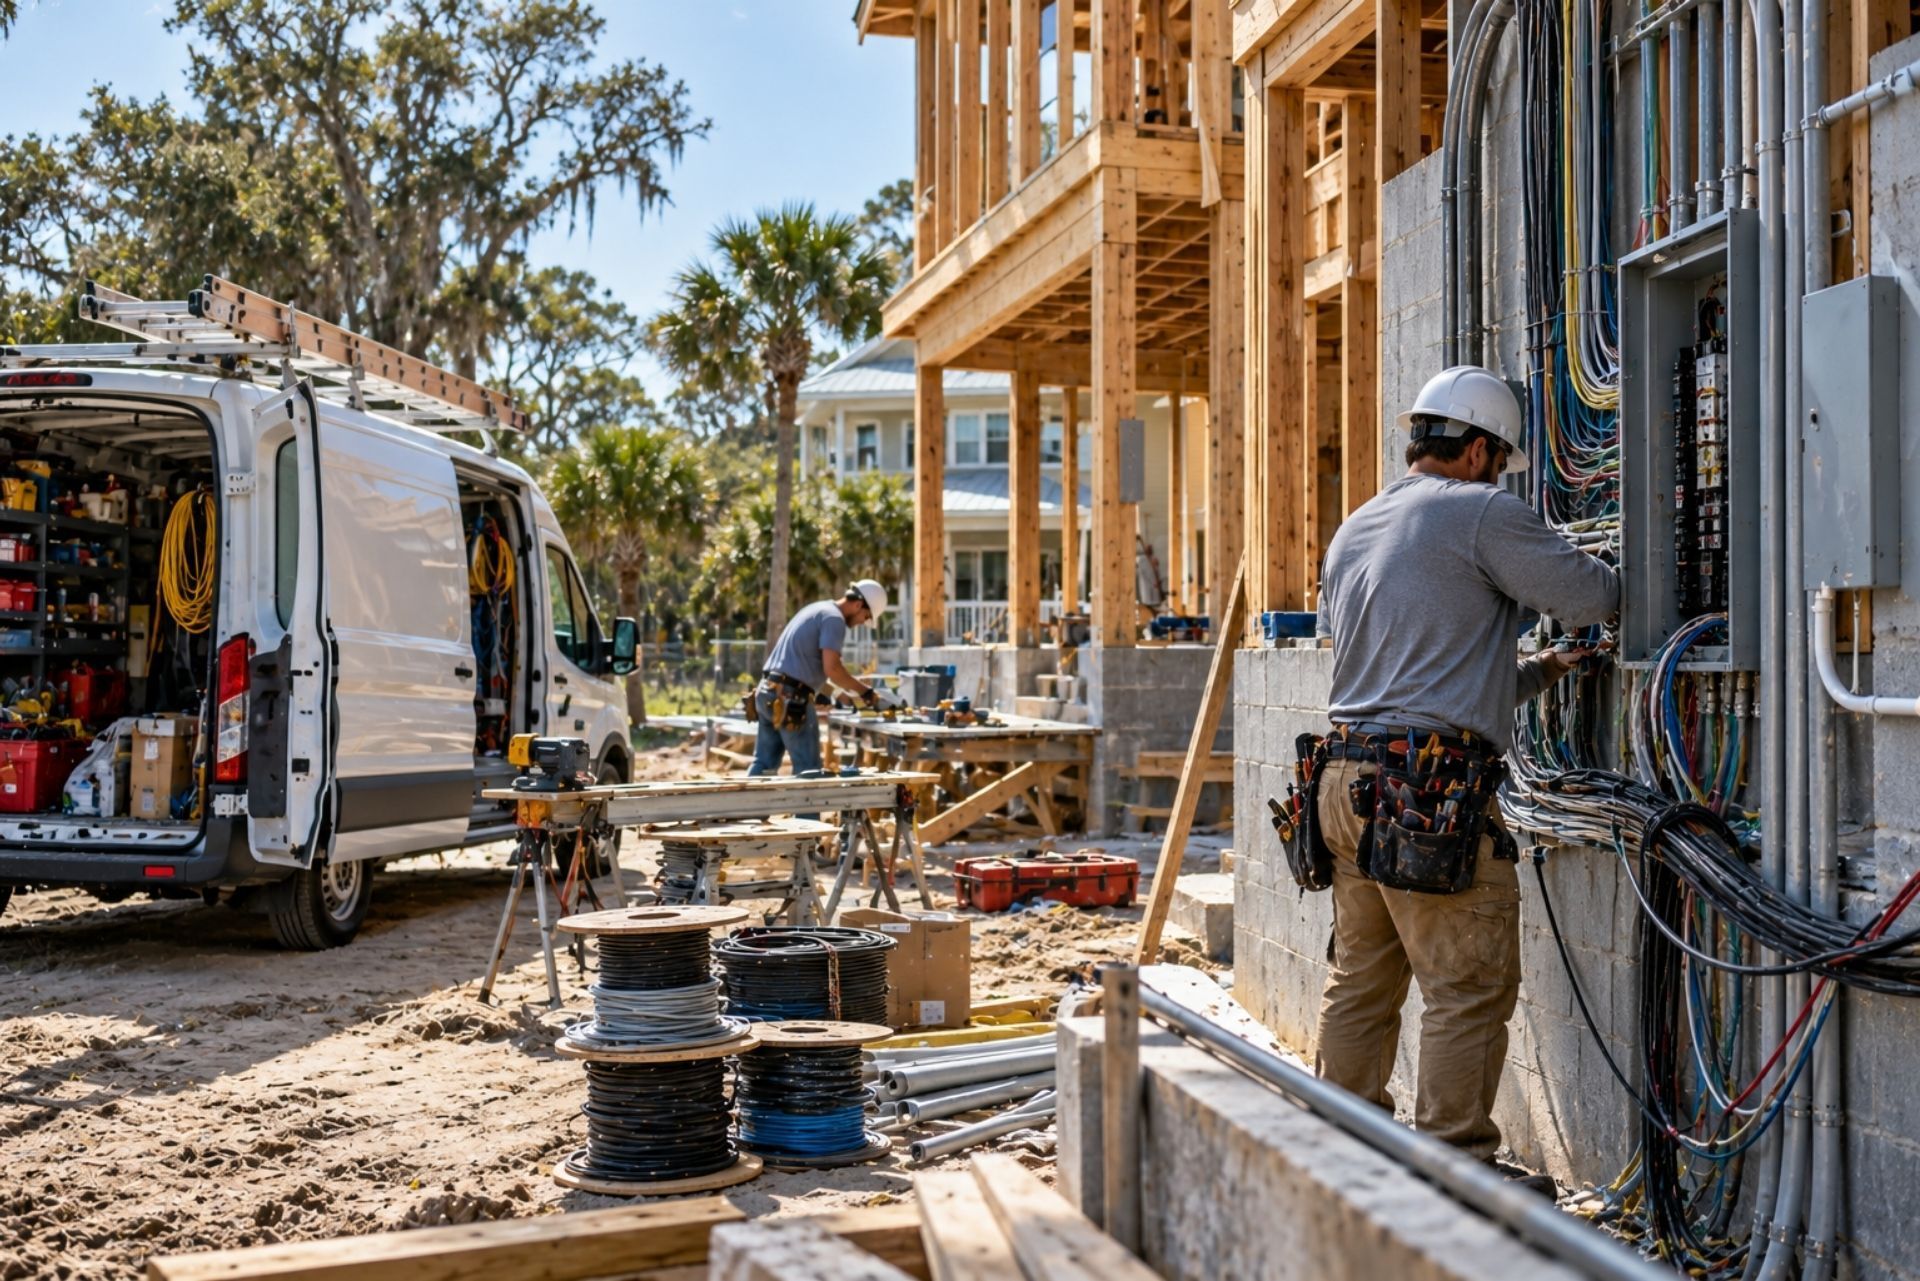
Picture a Myrtle Beach electrician pulling a panel upgrade on a beach house in August. A helper drops a meter base on the homeowner's tile floor, the van parked outside gets clipped by a tourist, and the $14,000 worth of testers and benders in the back suddenly feels very exposed. One afternoon can put four different policies to work.
That's the reality of running an electrical business in South Carolina. Your risks don't fit neatly into one box, and neither does your insurance. Licensing boards want proof of bonding, general contractors want certificates before you set foot on site, and the state has firm rules about covering your crew.
This guide walks through electrical contractor insurance in South Carolina piece by piece: general liability, tools and equipment, commercial auto, workers' compensation, bonds, and what drives your costs. You'll also find a residential vs. commercial comparison, an FAQ, and the mistakes we see contractors make most often when they shop on price alone.
The goal is simple. You should finish this with a clear sense of what you actually need, what you can skip, and which questions to ask before you sign anything.
Essential Insurance Coverages for South Carolina Electricians
Most electrical contractors need a core package of three policies before they ever think about extras. Each one covers a different kind of loss, and gaps between them are where claims get denied.
General Liability and Property Damage
General liability pays when your work injures someone or damages property that isn't yours. For electricians, the classic claim is a fire traced back to a loose connection or an overloaded circuit months after the job closed out. That's a "completed operations" claim, and it's the reason your GL policy matters long after you've been paid.
Watch for a few policy details that trip people up. Some cheaper policies exclude completed operations or cap it at a lower limit. Others carry a "your work" exclusion that won't pay to redo your own faulty wiring, only the resulting damage to the drywall, furniture, or building. Many general contractors also require you to name them as an additional insured, so confirm your carrier offers that endorsement before bidding.
Tools and Inland Marine Coverage
Your GL policy won't pay a dime if someone breaks into your van and steals your gear. That's the job of an inland marine or tools and equipment floater, which follows your equipment from the shop to the jobsite to the truck.
Pay attention to how the policy values a loss. Actual cash value subtracts depreciation, so a five-year-old thermal camera might pay out a fraction of what a new one costs. Replacement cost is worth the higher premium for most electricians. The market is favorable right now: carrier appetite has expanded capacity, letting contractors negotiate higher limits as equipment values climb. If you've added a trencher or lift since your last renewal, now's a good time to raise your schedule.
Commercial Auto for Service Vans
Personal auto policies typically exclude vehicles used primarily for business. If your van is titled to the business, wrapped with your logo, or loaded with inventory, you need commercial auto.
South Carolina's minimum liability is 25/50/25, which means $25,000 per person for injury, $50,000 per accident, and $25,000 for property damage. That's far too low for a working van. One rear-end collision on I-26 involving a newer SUV can blow past $25,000 in property damage alone. Most contractors we work with carry at least $1 million combined single limit, and many GCs require it.


Your CSP agent
Lawson Walker, CIC
Insurance Sales
On this page
CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.
From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.
By City
Fine Arts and High-Value Specialized Goods
Galleries, auction houses, and even corporate offices with art collections need specialized coverage. Standard property policies cap fine art at absurdly low limits, sometimes $2,500 per item. A fine arts floater provides agreed-value coverage, meaning you and the insurer agree on the item's worth upfront. If it's damaged or stolen, that's what you get paid.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Computer Equipment and Data Storage
Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.
South Carolina Workers' Compensation Requirements
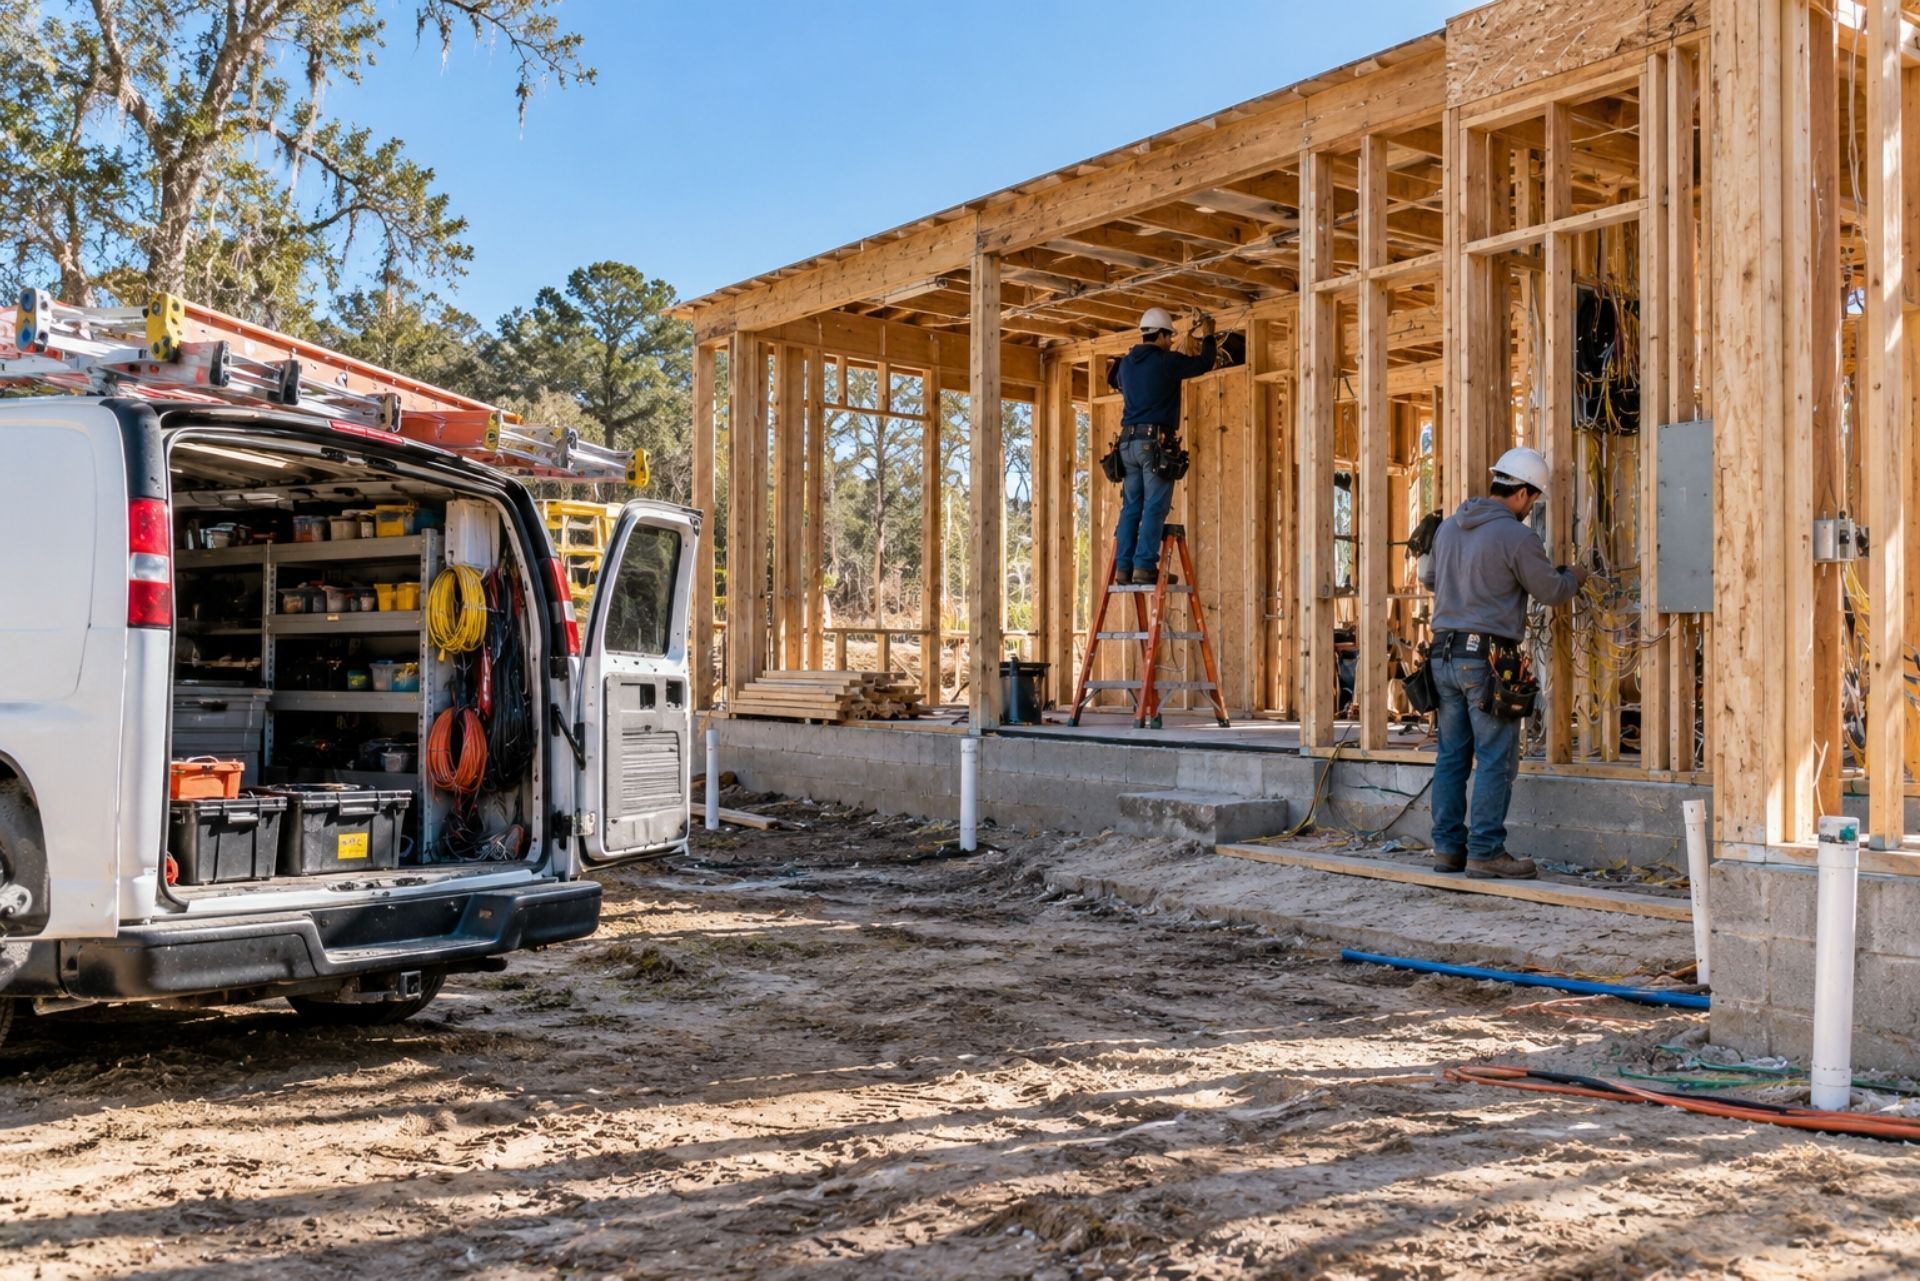
South Carolina employers with four or more employees, including part-time and seasonal workers, must carry workers' comp under Title 42 of the state code. That count catches a lot of small shops off guard. Two full-time electricians, an apprentice, and a part-time office manager equals four.
Even if you're under the threshold, skipping coverage is risky. General contractors almost always require subcontractors to show a certificate. If you can't produce one, the GC's carrier may charge them for covering your crew, and that cost lands back on you, or you lose the bid entirely. Uninsured subs can also become the GC's statutory employees, which makes you an unwelcome subcontractor fast.
Benefit levels matter for pricing. For injuries on or after January 1, 2026, the state's maximum weekly compensation rate is $1,189.94. An electrician who falls from a ladder and misses six months of work can generate a sizable lost-wage claim on top of medical bills.
One common mistake: misclassifying workers as 1099 contractors to avoid premiums. If that "independent" helper uses your tools, follows your schedule, and works only for you, the state will likely treat him as an employee. A payroll audit can produce a surprise bill, and an injury claim without coverage can be far worse.

Factors That Influence Your Premium Costs
Several variables drive what you'll pay:
- Specialty: Neurosurgeons pay far more than internists
- Claims history: Prior claims increase your rates, sometimes dramatically
- Location: Urban areas with higher jury awards tend to cost more
- Policy type: Occurrence policies cost more than claims-made
- Coverage limits: Higher limits mean higher premiums
- Years in practice: New physicians sometimes pay less initially on claims-made policies (the "step" or "mature" rate system)
The trend line isn't encouraging. Malpractice claims data for 2026 shows continued growth in both claim frequency and severity, meaning premiums are likely to keep rising. Shopping your coverage through an independent agency that compares multiple carriers can save you thousands annually without sacrificing protection.
For most commercial projects, extended coverage with appropriate endorsements is the smarter choice. The premium difference is often modest compared to the potential gap in coverage.
Surety Bonds and Licensing Compliance
Bonds aren't insurance for you. They protect your customer and the state if you fail to finish a job or follow licensing rules. If the surety pays a claim, it expects you to pay it back.
Requirements depend on your license type:
- Residential specialty electrical contractors must provide a flat $10,000 surety bond for projects exceeding $5,000.
- Commercial electrical contractors meet financial responsibility through bonds tiered by project group limits, ranging from $7,000 for Group 1 up to $300,000 for Group 5.
Your group classification determines how large a job you can legally bid. Contractors who want to move from Group 2 to Group 3 work need to increase their bond before chasing those projects, not after winning one.
Bond pricing is usually a percentage of the bond amount, driven heavily by personal credit and business financials. Clean credit can mean a modest annual cost; weaker credit can push it much higher or require collateral. Keep your bond renewals on the same calendar as your license renewal so nothing lapses mid-project.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
This is a policy feature that doesn't get enough attention. A consent-to-settle clause gives you the right to approve or reject any settlement offer your insurer wants to make. Without it, your carrier can settle a claim you believe is meritless, and that settlement goes on your record.
Some policies include a "hammer clause" instead: if you refuse a settlement the insurer recommends and the case goes to trial with a worse outcome, you're responsible for the difference. Understanding this clause before you buy a policy is critical. At CSP Insurance Services, their team walks clients through these policy details line by line, which matters because the fine print in malpractice policies can have career-altering consequences.
The Role of Consent-to-Settle Clauses
Errors and Omissions (E&O) for Design Flaws
If your shop does any design work, engineering consultation, or CAD/CAM programming for clients, E&O insurance is essential. This covers claims where your professional judgment or technical expertise leads to a client's financial loss.
A common scenario: your shop designs a custom fixture based on a client's rough specifications, the fixture fails during production, and the client claims your design was flawed. Without E&O coverage, you're defending that claim and paying any settlement from your own funds. Product recall insurance trends in 2026 show that insurers are paying closer attention to design-related exposures, which means getting E&O in place now is smarter than waiting until underwriting tightens further.
Comparing Coverage Needs: Residential vs. Commercial Work
A two-person crew doing service calls in Florence and a 15-person shop wiring warehouses in Rock Hill face very different exposures. Here's how needs typically shift:
| Coverage Area | Residential Focus | Commercial Focus |
|---|---|---|
| General liability limits | $1M per occurrence often enough | $1M/$2M plus umbrella common |
| Additional insured requests | Rare | Standard on most contracts |
| Bond requirement | $10,000 flat for jobs over $5,000 | $7,000 to $300,000 by group |
| Tools coverage | Hand tools, testers, ladders | Adds lifts, trenchers, rented gear |
| Workers' comp | Often small crews near the threshold | Nearly always required |
| Contract review needs | Simple work orders | Indemnity and waiver clauses |
Commercial contracts deserve extra scrutiny. Many include waiver of subrogation and primary/non-contributory wording that your policies must support with specific endorsements. Signing a contract your insurance can't match leaves you personally on the hook.
Residential electricians in coastal counties have their own wrinkle. After hurricanes and tropical storms, demand for generator installs and storm repair spikes. That's great for business, but it can push you into work your policy classifies differently, such as roofing-adjacent tasks or larger projects. Tell your agent before you take on new types of work.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
FAQ: What counts as a disability? Does it cover mental health? Are benefits taxable?
What qualifies as a disability under most group plans? Most policies define disability as the inability to perform the essential duties of your own occupation (for the first 1-2 years) and later shift to an "any occupation" standard. The exact definition varies by carrier and policy, so reading the contract language matters.
Does disability insurance cover mental health conditions? Yes, most modern group disability policies cover mental health conditions like depression, anxiety, and PTSD. However, many policies limit mental health claims to 24 months of benefits, even if the overall policy pays to age 65. Ask about this limitation before you buy.
Are disability benefits taxable? It depends on who pays the premium. If the employer pays, benefits are taxable to the employee. If the employee pays with after-tax dollars, benefits are received tax-free.
Can employees receive both workers' comp and disability benefits? Generally, no. Most disability policies include an offset provision that reduces benefits by the amount of workers' compensation received. The two programs are designed to complement each other, not stack.
Is there a waiting period before new employees can enroll? Most group plans allow employers to set an eligibility waiting period, commonly 30, 60, or 90 days. South Carolina doesn't regulate this waiting period for disability coverage, so it's up to the employer.
What happens if an employee is partially disabled? Many LTD policies include a partial or residual disability benefit that pays a reduced amount if the employee can work part-time but not full-time. This feature encourages return-to-work efforts while still providing financial support.
Factors That Influence Your Monthly Premiums
Several factors drive your builders risk premium. Project type matters: a wood-frame apartment complex costs more to insure than a concrete tilt-up warehouse. Location is significant, especially in South Carolina where coastal proximity affects wind/hail rates dramatically. A project in Florence will price very differently from one on the Grand Strand.
Other factors include project duration, the contractor's loss history, protective safeguards on-site (fencing, security cameras, fire extinguishers), and the deductible you choose. Premiums typically run between 1% and 4% of the total project value, though market conditions in early 2026 have pushed rates toward the lower end for well-managed projects.
Usually, yes. A single claim can increase your premiums by 10% to 30% or more, depending on the severity and outcome. Some carriers offer claims-free discounts that you'd lose. That said, a claim that's dismissed or results in no payout has less impact than one with a large settlement. Shopping your renewal through an independent agent can help offset rate increases by comparing offers from competing carriers.
FAQ: Will my rates go up if I have one claim?
Apartment complex insurance isn't a single policy: it's a coordinated set of coverages that work together to protect your buildings, your income, your employees, and your financial future. The right package includes general liability, commercial property, workers comp, commercial auto, and specialized add-ons like loss of rental income and equipment breakdown. Skipping any one of these creates a gap that a single bad claim can exploit.
The most effective approach is working with an independent agency that can compare options across multiple carriers. CSP Insurance Services has been helping South Carolina property owners build customized coverage programs since 1939, with direct access to real people who understand multifamily risk. If you're unsure whether your current coverage matches your actual exposure, or if you're purchasing a new complex and need to build a policy from scratch, request a quote to get a personalized analysis of your insurance needs. A 20-minute conversation now can save you six figures when a claim hits.
Does general liability cover fuel spills?
Usually not. Most GL policies contain pollution exclusions that specifically exclude fuel spills and environmental contamination. You need a separate pollution liability policy to cover cleanup costs, third-party damages, and regulatory fines from fuel releases.
Factors Influencing Insurance Costs in the Palmetto State
We can't give you a reliable price without seeing your operation, and you should be skeptical of anyone who quotes electrical contractor coverage sight unseen. Premiums swing based on several factors.
Payroll and revenue drive workers' comp and GL pricing directly. The type of work matters too: low-voltage and residential service usually rates lower than high-voltage industrial work. Location plays a role, with coastal areas near Charleston and the Grand Strand sometimes seeing higher property and auto pricing due to storm exposure and traffic density.
Auto is getting more expensive everywhere. Commercial auto premiums rose an average of roughly 4.5% to 4.93% as of Q2 2026, largely because sensors, cameras, and other vehicle technology make repairs costlier. Adding vans to your fleet, hiring younger drivers, or keeping drivers with violations on the policy will push that number higher.
Common Policy Limits and Deductibles
Most electricians land on $1 million per occurrence and $2 million aggregate for general liability, which satisfies the majority of contracts. Larger commercial jobs may require a $1 million to $5 million umbrella on top.
Deductibles are a lever you control. Raising a tools deductible from $500 to $1,000 can trim premium, but only if you can comfortably absorb that out-of-pocket hit after a theft. Don't raise deductibles so high that you'd avoid filing a legitimate claim.
How Claims History Impacts Premiums
Carriers look at your loss runs, typically covering the past three to five years. Frequent small claims often hurt more than one large one, because they signal ongoing risk. A string of tool theft claims, for instance, tells underwriters your vehicles or shop lack security.
For workers' comp, your experience modification rate compares your claims to similar businesses. A rate above 1.0 raises premiums and can disqualify you from some commercial bids. Safety programs, lockout/tagout training, and return-to-work plans help bring it down over time.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
This is a policy feature that doesn't get enough attention. A consent-to-settle clause gives you the right to approve or reject any settlement offer your insurer wants to make. Without it, your carrier can settle a claim you believe is meritless, and that settlement goes on your record.
Some policies include a "hammer clause" instead: if you refuse a settlement the insurer recommends and the case goes to trial with a worse outcome, you're responsible for the difference. Understanding this clause before you buy a policy is critical. At CSP Insurance Services, their team walks clients through these policy details line by line, which matters because the fine print in malpractice policies can have career-altering consequences.
The Role of Consent-to-Settle Clauses
Frequently Asked Questions About Electrical Insurance
Do I need insurance if I'm a one-person electrical business? Yes. You may not need workers' comp under the four-employee rule, but GL, commercial auto, and tools coverage still protect you, and most clients will ask for a certificate.
Does general liability cover my mistakes in wiring? It covers the damage your faulty work causes, like fire or injury. It usually won't pay to fix the wiring itself.
Can I use my personal truck for jobs? You can, but your personal auto policy may deny a claim if the vehicle is used mainly for business. A commercial auto policy or business-use endorsement closes that gap.
Is a surety bond the same as insurance? No. A bond protects your customer, and you must repay the surety for any claim it pays.
How fast can I get a certificate of insurance? Once your policy is active, an agency can usually issue a certificate the same day, which helps when a GC needs proof before you start.
Will hiring an apprentice affect my rates? It can. Added payroll raises workers' comp premiums, and inexperienced workers may affect pricing depending on duties.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
FAQ: What counts as a disability? Does it cover mental health? Are benefits taxable?
What qualifies as a disability under most group plans? Most policies define disability as the inability to perform the essential duties of your own occupation (for the first 1-2 years) and later shift to an "any occupation" standard. The exact definition varies by carrier and policy, so reading the contract language matters.
Does disability insurance cover mental health conditions? Yes, most modern group disability policies cover mental health conditions like depression, anxiety, and PTSD. However, many policies limit mental health claims to 24 months of benefits, even if the overall policy pays to age 65. Ask about this limitation before you buy.
Are disability benefits taxable? It depends on who pays the premium. If the employer pays, benefits are taxable to the employee. If the employee pays with after-tax dollars, benefits are received tax-free.
Can employees receive both workers' comp and disability benefits? Generally, no. Most disability policies include an offset provision that reduces benefits by the amount of workers' compensation received. The two programs are designed to complement each other, not stack.
Is there a waiting period before new employees can enroll? Most group plans allow employers to set an eligibility waiting period, commonly 30, 60, or 90 days. South Carolina doesn't regulate this waiting period for disability coverage, so it's up to the employer.
What happens if an employee is partially disabled? Many LTD policies include a partial or residual disability benefit that pays a reduced amount if the employee can work part-time but not full-time. This feature encourages return-to-work efforts while still providing financial support.
Factors That Influence Your Monthly Premiums
Several factors drive your builders risk premium. Project type matters: a wood-frame apartment complex costs more to insure than a concrete tilt-up warehouse. Location is significant, especially in South Carolina where coastal proximity affects wind/hail rates dramatically. A project in Florence will price very differently from one on the Grand Strand.
Other factors include project duration, the contractor's loss history, protective safeguards on-site (fencing, security cameras, fire extinguishers), and the deductible you choose. Premiums typically run between 1% and 4% of the total project value, though market conditions in early 2026 have pushed rates toward the lower end for well-managed projects.
Usually, yes. A single claim can increase your premiums by 10% to 30% or more, depending on the severity and outcome. Some carriers offer claims-free discounts that you'd lose. That said, a claim that's dismissed or results in no payout has less impact than one with a large settlement. Shopping your renewal through an independent agent can help offset rate increases by comparing offers from competing carriers.
FAQ: Will my rates go up if I have one claim?
Apartment complex insurance isn't a single policy: it's a coordinated set of coverages that work together to protect your buildings, your income, your employees, and your financial future. The right package includes general liability, commercial property, workers comp, commercial auto, and specialized add-ons like loss of rental income and equipment breakdown. Skipping any one of these creates a gap that a single bad claim can exploit.
The most effective approach is working with an independent agency that can compare options across multiple carriers. CSP Insurance Services has been helping South Carolina property owners build customized coverage programs since 1939, with direct access to real people who understand multifamily risk. If you're unsure whether your current coverage matches your actual exposure, or if you're purchasing a new complex and need to build a policy from scratch, request a quote to get a personalized analysis of your insurance needs. A 20-minute conversation now can save you six figures when a claim hits.
Does general liability cover fuel spills?
Usually not. Most GL policies contain pollution exclusions that specifically exclude fuel spills and environmental contamination. You need a separate pollution liability policy to cover cleanup costs, third-party damages, and regulatory fines from fuel releases.
Loss Discovery vs. Loss Sustained Forms
Crime policies come in two forms, and the difference matters. A loss-sustained form covers losses that occur during the policy period, even if discovered later (within a specified window). A loss-discovery form covers losses discovered during the policy period, regardless of when they occurred, as long as you didn't know about them before the policy started.
Discovery forms are more common and generally more favorable for the insured. If an employee has been stealing for two years and you discover it during your current policy period, a discovery form responds. Make sure you understand which form your policy uses.
Making the Right Choice for Your Electrical Business
The right package for a South Carolina electrician starts with four pieces: general liability with solid completed operations coverage, a tools floater at replacement cost, commercial auto well above the 25/50/25 minimum, and workers' comp once your headcount hits four. Add the correct license bond for your work type, and match your endorsements to the contracts you actually sign.
The cheapest quote often hides the exclusions that hurt most. As an independent agency serving South Carolina since 1939, CSP Insurance Services compares multiple carriers and talks with you directly, with no call centers involved, to build coverage around your crew and projects.
If you're bidding bigger jobs, adding vans, or just aren't sure your current policies line up, it's worth a second look. Request a Quote and we'll walk through your exposures together, so your next certificate request is the easy part of the job.
About the author
Lawson Walker, CIC
I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.
As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.
Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience

1939
Serving SC
Most Requested
Core business coverage.
The policies most South Carolina businesses start with.

Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Workers Compensation
Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.

Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

General Liability
Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.

Inland Marine
Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.

Business Owners (BOP)
A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Personal Insurance
Coverage for your home, vehicles, and family.
Protect what matters most with personal policies shopped across our carriers.
Home
Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.
Auto
South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.
Umbrella
When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.
Boat
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Condo
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Industries We Serve
Specialized coverage for your industry.
Every industry carries its own risk. We help South Carolina businesses protect what they've built.

Restaurants
Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.

Manufacturers
From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.

Healthcare Providers
Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
How It Works
Getting covered is simple.
Four steps, one real person from start to finish.
We compare carriers
We shop options across our carriers to find strong protection at a fair price.
We compare several carriers to find a policy that fits you, not one company's products.
Multi-carrier choice
Claims advocacy
When a claim happens, we stand in your corner and help move it forward with your carrier.
Local SC roots
We live and work in Florence and understand the risks your community faces because we face them too.
Client Reviews
Why clients choose CSP.
Independent advice, real people, and decades of local roots.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
FAQs
Questions, answered.
Straight answers about working with an independent agency.

What does an independent insurance agency do?
An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.
Do you cover both personal and business insurance?
Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.
How long has CSP been in business?
CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.
Will I work with a real person?
Always. No call centers and no chatbots — you work with a local team member who knows your account.
Which areas do you serve?
We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.
How do I get a quote?
Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.
How It Works
Insurance tips & updates.
Plain-language guidance to help you make confident decisions.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Get a Quote
Let's find your coverage.
Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.
2420 Hoffmeyer Road, Suite D
Florence, SC 29501
Mon–Fri 8:30am – 5:00pm