
CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
Hospital bills, treatment, and prescriptions for a work-related injury or illness.
Medical expenses
Claims history
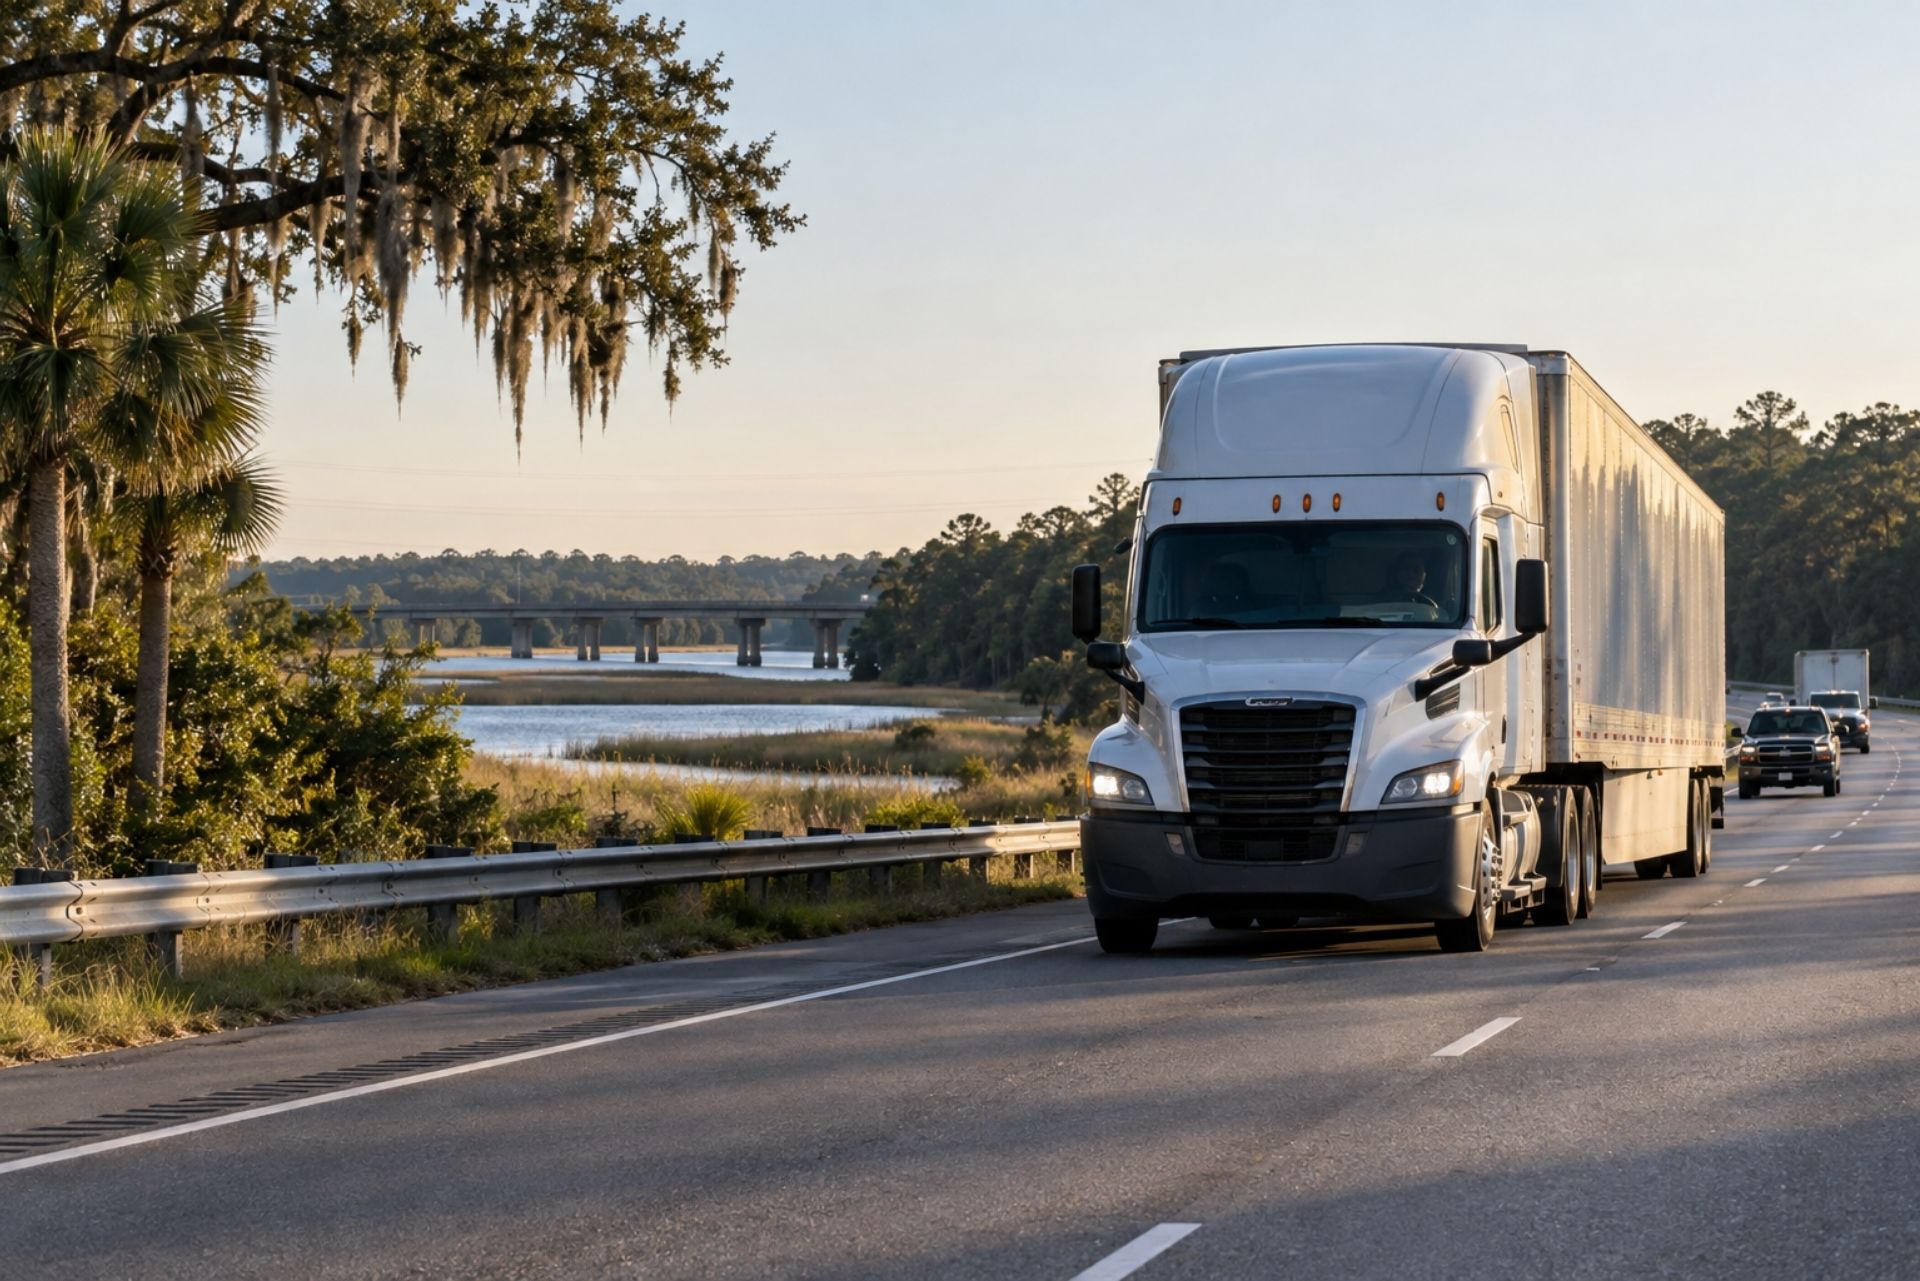
A single accident involving a loaded tractor-trailer on I-95 near Florence or along the congested stretch of I-26 through Columbia can generate claims well into six or seven figures. For motor carriers operating in South Carolina, the insurance program you build isn't just a regulatory checkbox: it's the financial backbone that determines whether your business survives a bad day on the road. Between federal filing requirements, state-specific mandates from the SC Department of Insurance, and the practical realities of protecting drivers, cargo, and equipment, there's a lot to get right.
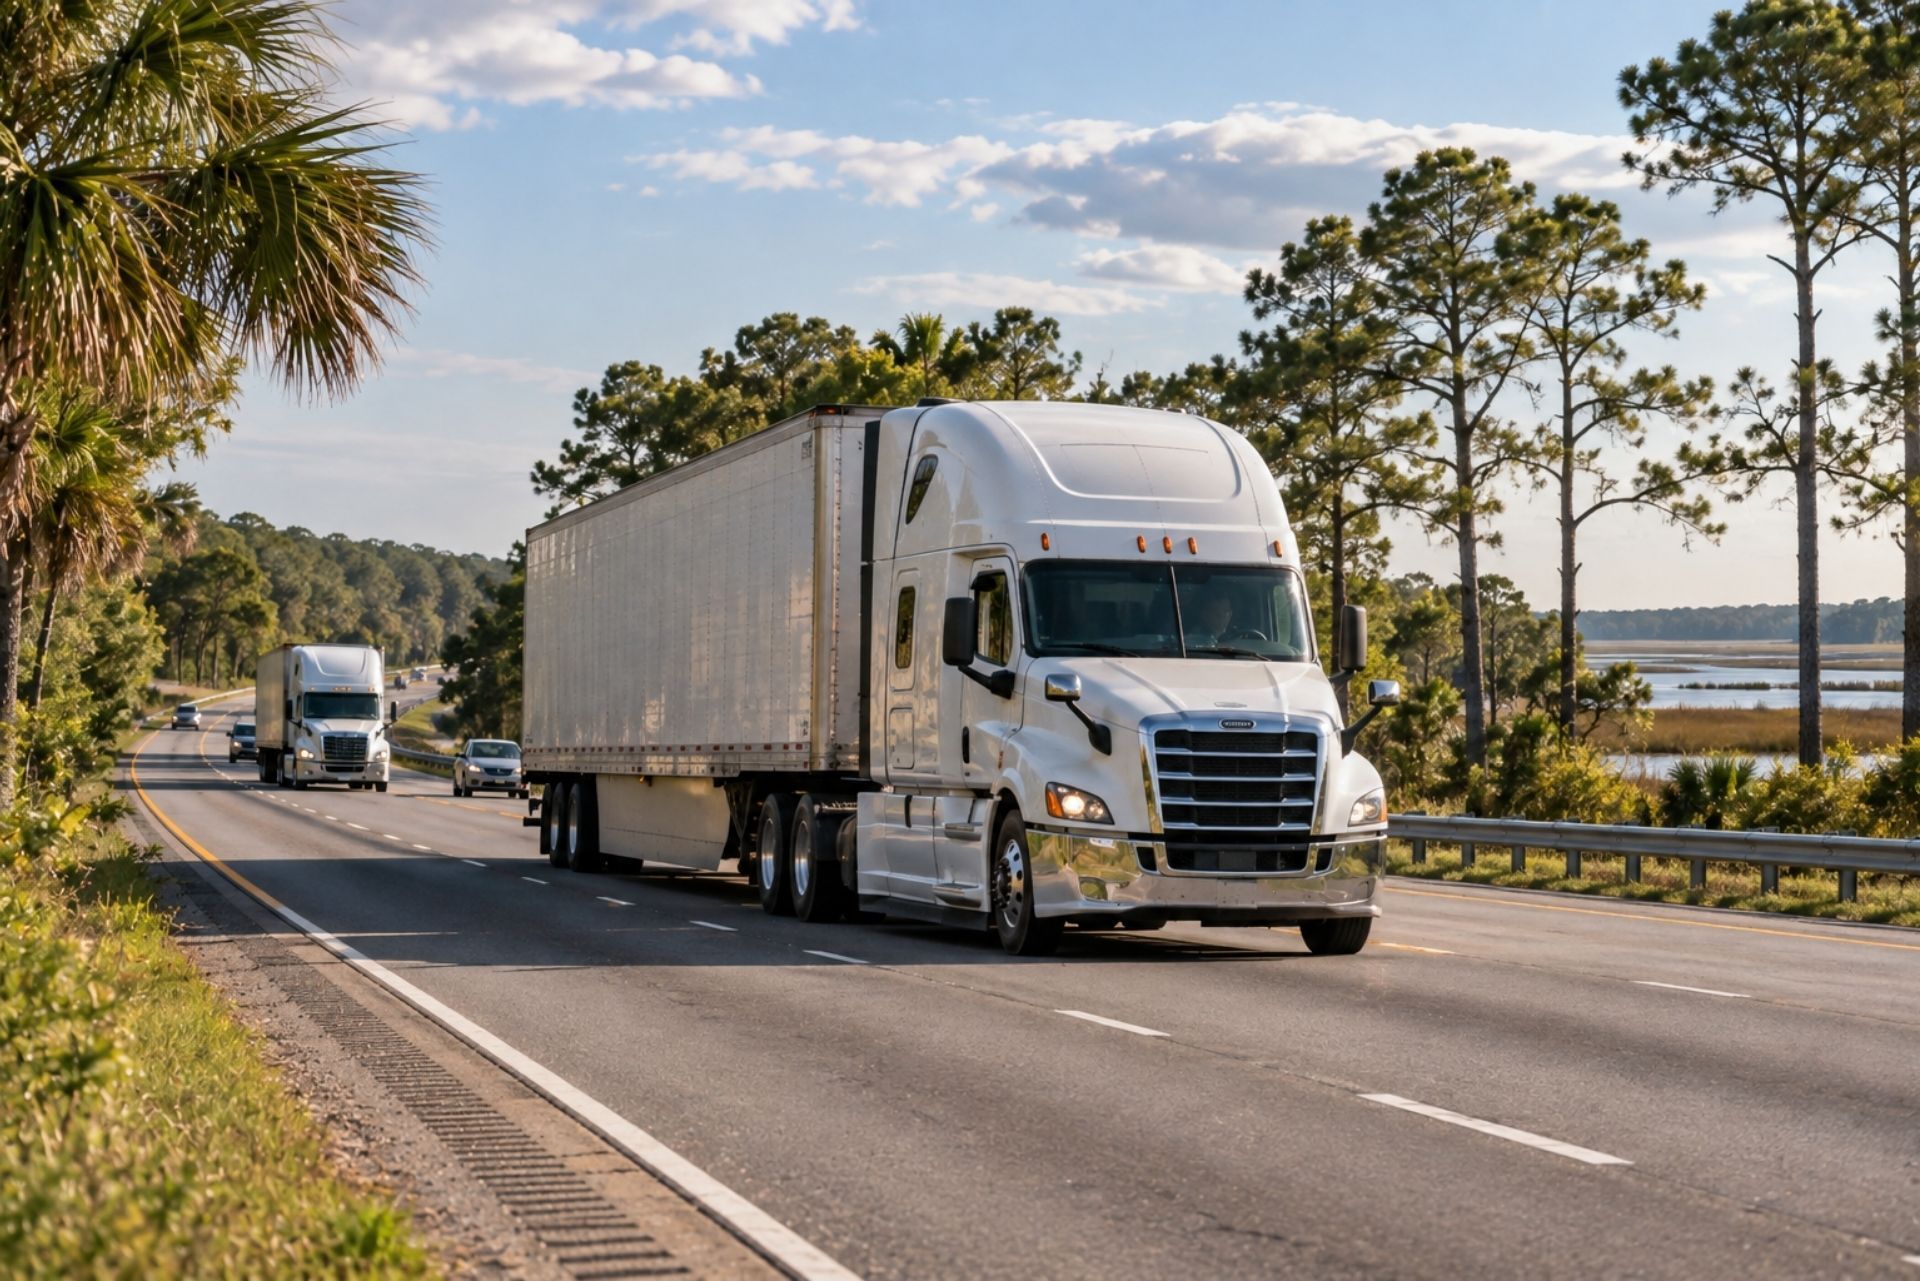
South Carolina's trucking insurance costs have been climbing steadily, driven by nuclear verdicts and rising repair expenses. Trucking insurance costs have outpaced revenue growth at many of America's largest fleets, and smaller operators feel the squeeze even more. Whether you're running a three-truck operation out of Rock Hill or managing a fleet hauling goods along the Myrtle Beach corridor, understanding the full picture of motor carrier insurance in South Carolina: primary liability, cargo coverage, physical damage, FMCSA filings, workers' comp, and the factors driving your premiums: is essential to keeping your business on the road.
Core Insurance Requirements for South Carolina Motor Carriers
South Carolina requires commercial motor vehicles to carry minimum liability insurance, but the specifics depend on the type of freight, the vehicle's weight, and whether you operate intrastate or interstate. The state's minimum auto liability split limits of 25/50/25 apply to personal vehicles, not commercial trucks. Motor carriers face significantly higher requirements dictated by both state law and federal regulations.
Getting this wrong isn't a minor paperwork issue. Operating without proper coverage can result in your authority being revoked, your vehicles placed out of service, and
personal liability exposure that could bankrupt an owner-operator overnight.
Primary Liability Limits and State Mandates
For interstate carriers, the FMCSA sets minimum liability requirements based on what you haul. General freight carriers operating vehicles over 10,001 pounds need at least $750,000 in primary liability coverage. Carriers transporting hazardous materials face minimums of $1 million or $5 million, depending on the specific commodities.
Most experienced fleet managers carry well above these minimums. A single fatality claim in South Carolina can easily exceed $2 million, and rising insurance costs across the trucking industry reflect the growing frequency of large jury awards. Carrying $1 million in primary liability for general freight has become the practical standard for carriers who want real protection, not just compliance.
Intrastate-only carriers in South Carolina should check with the SC Department of Insurance for state-specific minimums, which can differ from federal thresholds. The SC DOI publishes bulletins and orders that occasionally update these requirements.
MCSA Filings: BMC-91X and Form E
If you operate interstate, you need proof of insurance on file with the FMCSA. This comes in two forms. The BMC-91X is filed by your insurance company directly with the FMCSA, certifying that your liability policy meets federal minimums. Form E serves a similar purpose for surety bonds.
These filings aren't optional, and they're not something you handle yourself: your insurer or agent submits them on your behalf. The catch is that not every insurance company is set up to handle FMCSA filings efficiently. Delays in filing can hold up your operating authority for weeks. Working with an agency that has deep familiarity with FMCSA insurance requirements can save you significant headaches during the authority application process.
One thing to keep in mind: if your policy lapses or is cancelled, your insurer is required to notify the FMCSA. That notification triggers a countdown, and if you don't have replacement coverage filed within the grace period, your authority gets revoked.


Your CSP agent
Lawson Walker, CIC
Insurance Sales
On this page
CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.
From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.
Protecting Assets with Cargo and Physical Damage Coverage
Liability insurance covers damage you cause to others. Cargo and physical damage coverage protect what belongs to you and your customers. These are separate policies with distinct structures, and skipping either one is a gamble most carriers can't afford.
Cargo Insurance: Protecting the Load
Cargo insurance covers the freight you're hauling if it's damaged, destroyed, or stolen during transit. The FMCSA requires a minimum of $5,000 in cargo coverage for most general freight carriers, but that number is laughably low for real-world operations. Most shippers and brokers require $100,000 to $250,000 in cargo coverage before they'll tender a load.
The type of freight matters enormously. A flatbed hauling lumber has a very different risk profile than a reefer carrying pharmaceuticals. Your cargo policy should match the commodities you actually haul, and you need to disclose those commodities accurately. A claim on undisclosed freight types is a fast path to a denial.
Theft is a growing concern in South Carolina, particularly at truck stops along I-95 and I-85. Cargo theft endorsements and trailer interchange coverage are worth discussing with your agent, especially if you're running through high-risk corridors.
Physical Damage: Collision vs. Comprehensive
Physical damage coverage breaks into two pieces. Collision pays for damage to your truck or trailer from an accident, regardless of fault. Comprehensive covers everything else: theft, fire, vandalism, hail, and windstorm damage.
South Carolina's coastal exposure makes comprehensive coverage particularly important. Hurricanes and severe storms regularly impact the Lowcountry and Grand Strand areas, and a truck parked at a Myrtle Beach terminal during a major storm can sustain tens of thousands in damage. If you're financing or leasing your equipment, your lender will require both collision and comprehensive coverage anyway.
Deductibles on physical damage policies typically range from $1,000 to $5,000. Choosing a higher deductible lowers your premium but increases your out-of-pocket cost per incident. For fleets with older equipment, some carriers drop collision coverage entirely and self-insure that risk: a reasonable strategy if the truck's value doesn't justify the premium.

Workers' Compensation for South Carolina Trucking Firms
South Carolina requires workers' compensation insurance for any employer with four or more employees. Trucking is classified as a high-risk industry, so the premiums reflect that reality. The SC Workers' Compensation Commission publishes current compensation rates that determine benefit levels for injured workers.
The classification codes used to rate your workers' comp policy matter. Drivers, dock workers, and office staff each fall under different workers' comp class codes, and misclassifying employees is one of the most common audit triggers. If your drivers are coded incorrectly, you could face a significant premium adjustment at audit time: sometimes tens of thousands of dollars.
Owner-operators present a unique challenge. If they're truly independent contractors, they're typically not covered under your workers' comp policy. But South Carolina courts have reclassified contractors as employees in cases where the carrier exercised too much control over the work. That reclassification can create retroactive premium liability and penalties. Getting the independent contractor relationship documented properly is critical.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Coverage Comparison: Basic vs. Comprehensive Protection
The gap between minimum compliance and genuine protection is enormous in trucking insurance. Here's a side-by-side look at what basic coverage provides versus what a well-structured program includes.
Comparison Chart: Minimum vs. Recommended Limits
| Coverage Type | Minimum / Basic | Recommended |
|---|---|---|
| Primary Liability | $750,000 (FMCSA minimum) | $1,000,000+ |
| Cargo | $5,000 (FMCSA minimum) | $100,000 - $250,000 |
| Physical Damage (Collision) | Not required by law | Full value, $2,500 deductible |
| Physical Damage (Comprehensive) | Not required by law | Full value, $1,000 deductible |
| Workers' Compensation | Required with 4+ employees | Statutory limits + employer's liability |
| Non-Trucking Liability | Not required | $1,000,000 (for owner-operators) |
| Trailer Interchange | Not required | $30,000 - $50,000 per trailer |
The minimum gets you legal. The recommended column keeps you in business after a serious claim. An agency like CSP Insurance Services, which has been matching South Carolina businesses with coverage since 1939, can help you find the right balance between cost and protection by comparing options across multiple carriers.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Factors Influencing Trucking Insurance Costs
Average annual premiums for a single semi-truck in South Carolina with a clean record range between $11,500 and $15,000 for basic liability coverage. That number can double or triple depending on several key variables.
Driver MVRs and Safety Ratings
Your drivers' motor vehicle records are the single biggest factor in your premium. A driver with a DUI, multiple speeding tickets, or an at-fault accident in the past three years can increase your per-truck cost by 30% to 50%. Some insurers won't write a policy at all if your driver pool has too many violations.
Your company's CSA scores and SMS percentiles also play a role. Carriers with poor safety ratings from the FMCSA pay significantly more, and some markets won't quote them. Investing in driver training, dash cameras, and ELD compliance pays dividends at renewal time.
Radius of Operation and Freight Type
A carrier running local routes within a 100-mile radius of Columbia pays less than one hauling freight coast to coast. Long-haul operations increase exposure to accidents, theft, and regulatory complexity across multiple states.
The type of freight you carry directly impacts cargo and liability premiums. Hauling general commodities is cheaper to insure than transporting hazardous materials, oversized loads, or high-value electronics. Transportation and logistics insurance specialists familiar with South Carolina's market can often find better rates for niche freight types than generalist agencies.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Common Questions About SC Trucking Insurance
Do I need trucking insurance if I only operate within South Carolina? Yes. Intrastate carriers still need liability coverage that meets state minimums, and most shippers require cargo insurance regardless of your operating radius.
Can I get insurance with a new MC number and no experience? You can, but expect to pay a premium. New ventures typically face rates 20% to 40% higher than established carriers. Building 12 to 24 months of clean operating history brings costs down significantly.
Does my personal auto policy cover my truck? No. Personal auto policies exclude commercial vehicles. You need a commercial auto or trucking-specific policy.
What happens if my FMCSA filing lapses? Your operating authority can be revoked. The FMCSA provides a short grace period after notification of cancellation, but operating without valid filings puts you at risk of being placed out of service during a roadside inspection.
Is non-trucking liability the same as bobtail insurance? They're similar but not identical. Non-trucking liability covers you when you're using the truck for personal purposes, not under dispatch. Bobtail coverage applies when you're driving without a trailer. Some policies combine both, but check the fine print.
How often should I shop my trucking insurance? Every 12 to 18 months, or whenever you add trucks, change freight types, or expand your operating radius. An independent agency can run quotes across multiple carriers quickly, which saves you from calling ten companies yourself.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Making the Right Choice for Your Fleet
Building the right insurance program for a South Carolina trucking operation means balancing federal requirements, state regulations, and the specific risks your fleet faces every day. Cutting corners on coverage saves money until the first serious claim, and then it can cost you everything.
The smartest approach is working with an independent agency that understands trucking: one that isn't locked into a single carrier's products and can shop the market on your behalf. CSP Insurance Services works with multiple insurers to build customized protection for motor carriers across South Carolina, from owner-operators in Florence to mid-size fleets based in Columbia.
If you're launching a new operation, renewing an existing policy, or just not sure whether your current coverage has gaps, reach out to get a professional review. You can request a quote and have a real person walk you through your options: no call centers, no chatbots, just straightforward advice from people who've been doing this for decades.
About the author
Lawson Walker, CIC
I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.
As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.
Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Most Requested
Core business coverage.
The policies most South Carolina businesses start with.

Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.

Workers Compensation
Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.

Commercial Auto
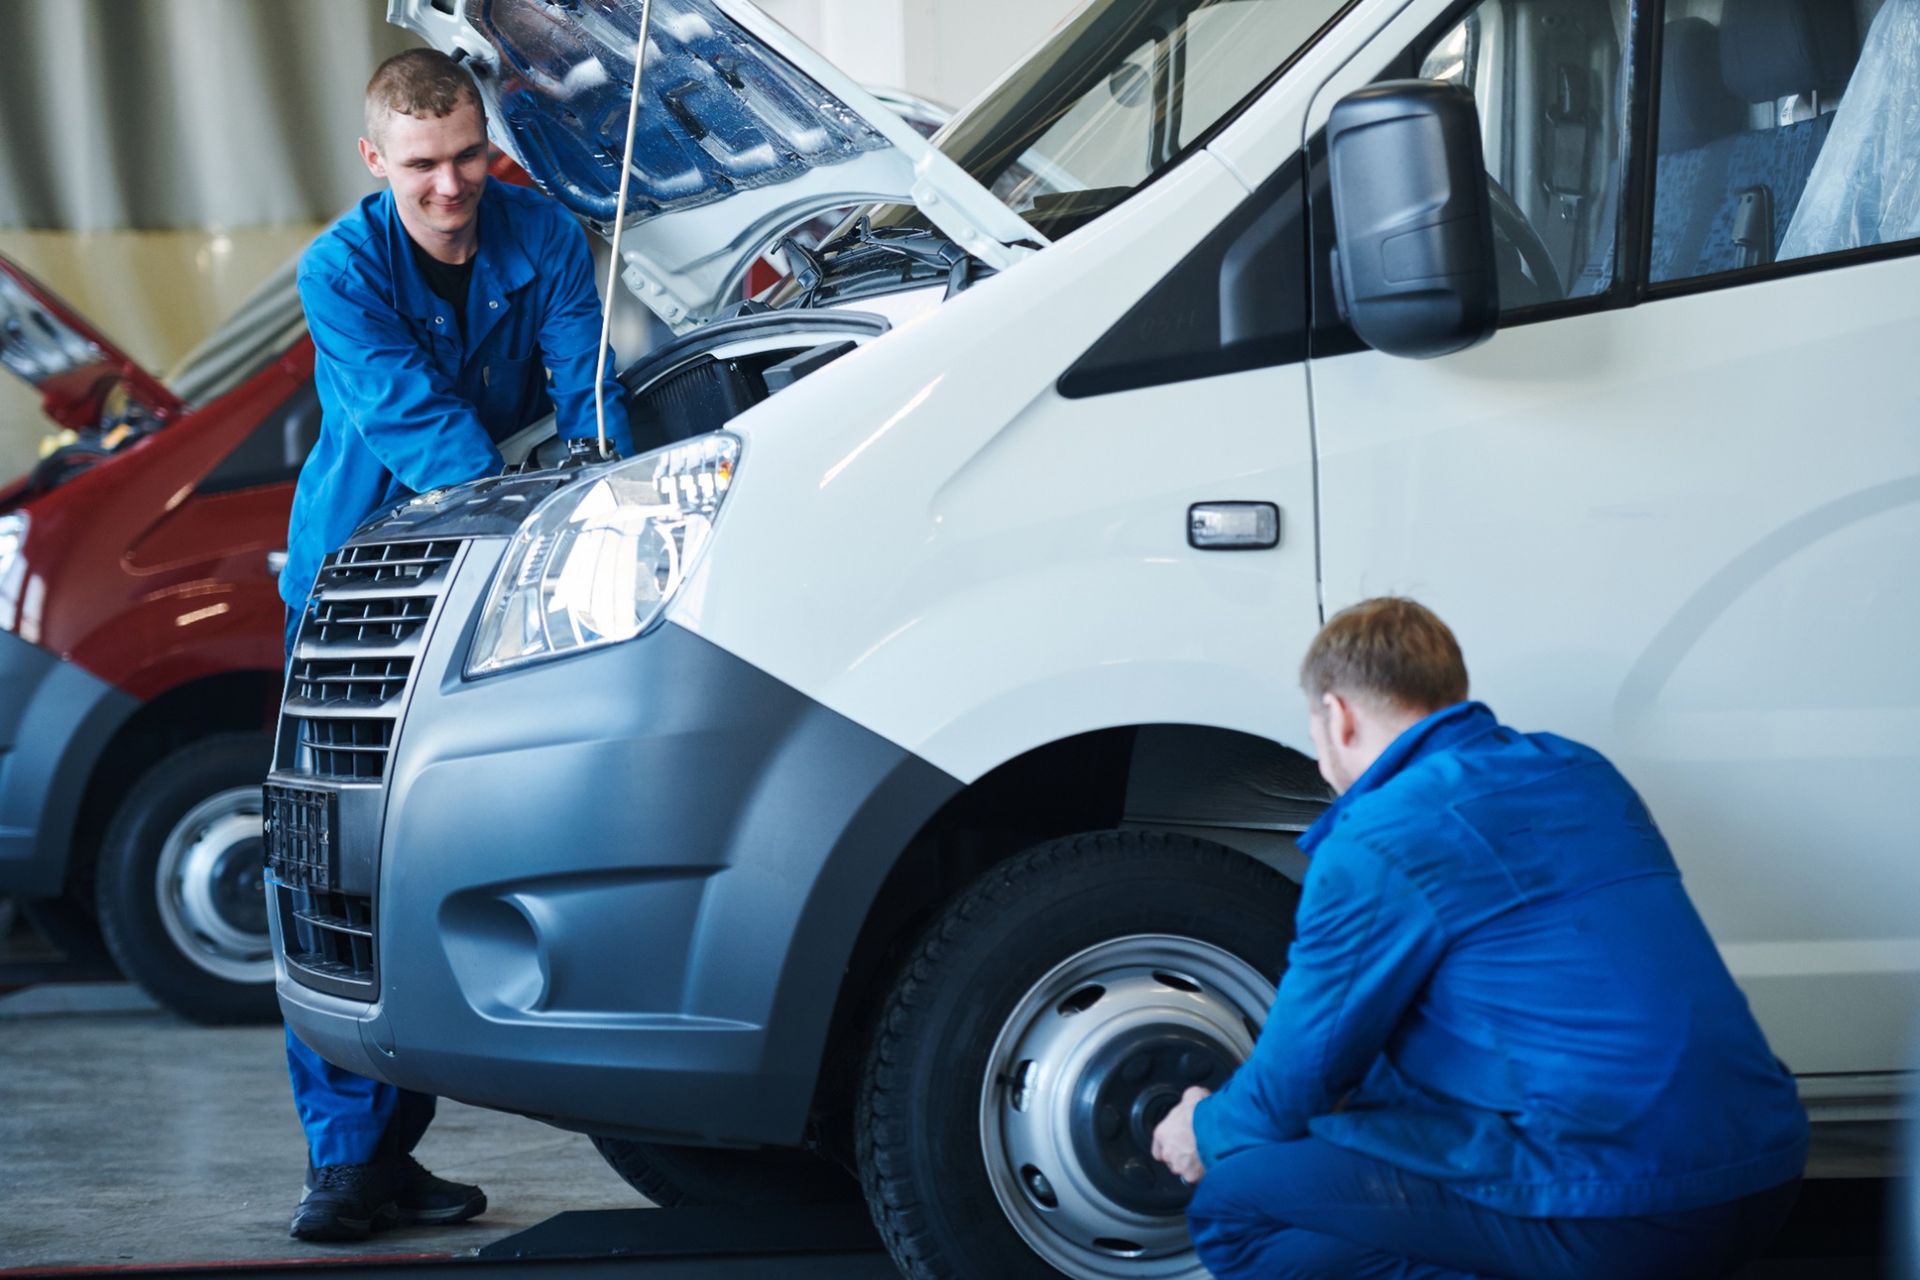
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.

General Liability
Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.

Inland Marine
Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.

Business Owners (BOP)
A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Personal Insurance
Coverage for your home, vehicles, and family.
Protect what matters most with personal policies shopped across our carriers.
Home
Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.
Auto
South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.
Umbrella
When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.
Boat
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Condo
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Industries We Serve
Specialized coverage for your industry.
Every industry carries its own risk. We help South Carolina businesses protect what they've built.

Restaurants
Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.

Manufacturers
From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.

Healthcare Providers
Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
How It Works
Getting covered is simple.
Four steps, one real person from start to finish.
We compare carriers
We shop options across our carriers to find strong protection at a fair price.
We compare several carriers to find a policy that fits you, not one company's products.
Multi-carrier choice
Claims advocacy
When a claim happens, we stand in your corner and help move it forward with your carrier.
Local SC roots
We live and work in Florence and understand the risks your community faces because we face them too.
Client Reviews
Why clients choose CSP.
Independent advice, real people, and decades of local roots.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
FAQs
Questions, answered.
Straight answers about working with an independent agency.

What does an independent insurance agency do?
An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.
Do you cover both personal and business insurance?
Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.
How long has CSP been in business?
CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.
Will I work with a real person?
Always. No call centers and no chatbots — you work with a local team member who knows your account.
Which areas do you serve?
We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.
How do I get a quote?
Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.
How It Works
Insurance tips & updates.
Plain-language guidance to help you make confident decisions.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience


1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Get a Quote
Let's find your coverage.
Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.
2420 Hoffmeyer Road, Suite D
Florence, SC 29501
Mon–Fri 8:30am – 5:00pm