
CSP Insurance Services was founded in 1939, when Clifford Cormell joined Earnest Streett to sell insurance in Florence. More than 80 years later, we still answer the phone ourselves. No call centers, no chatbots — just a local team that knows your name and your policy.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
Hospital bills, treatment, and prescriptions for a work-related injury or illness.
Medical expenses
Claims history
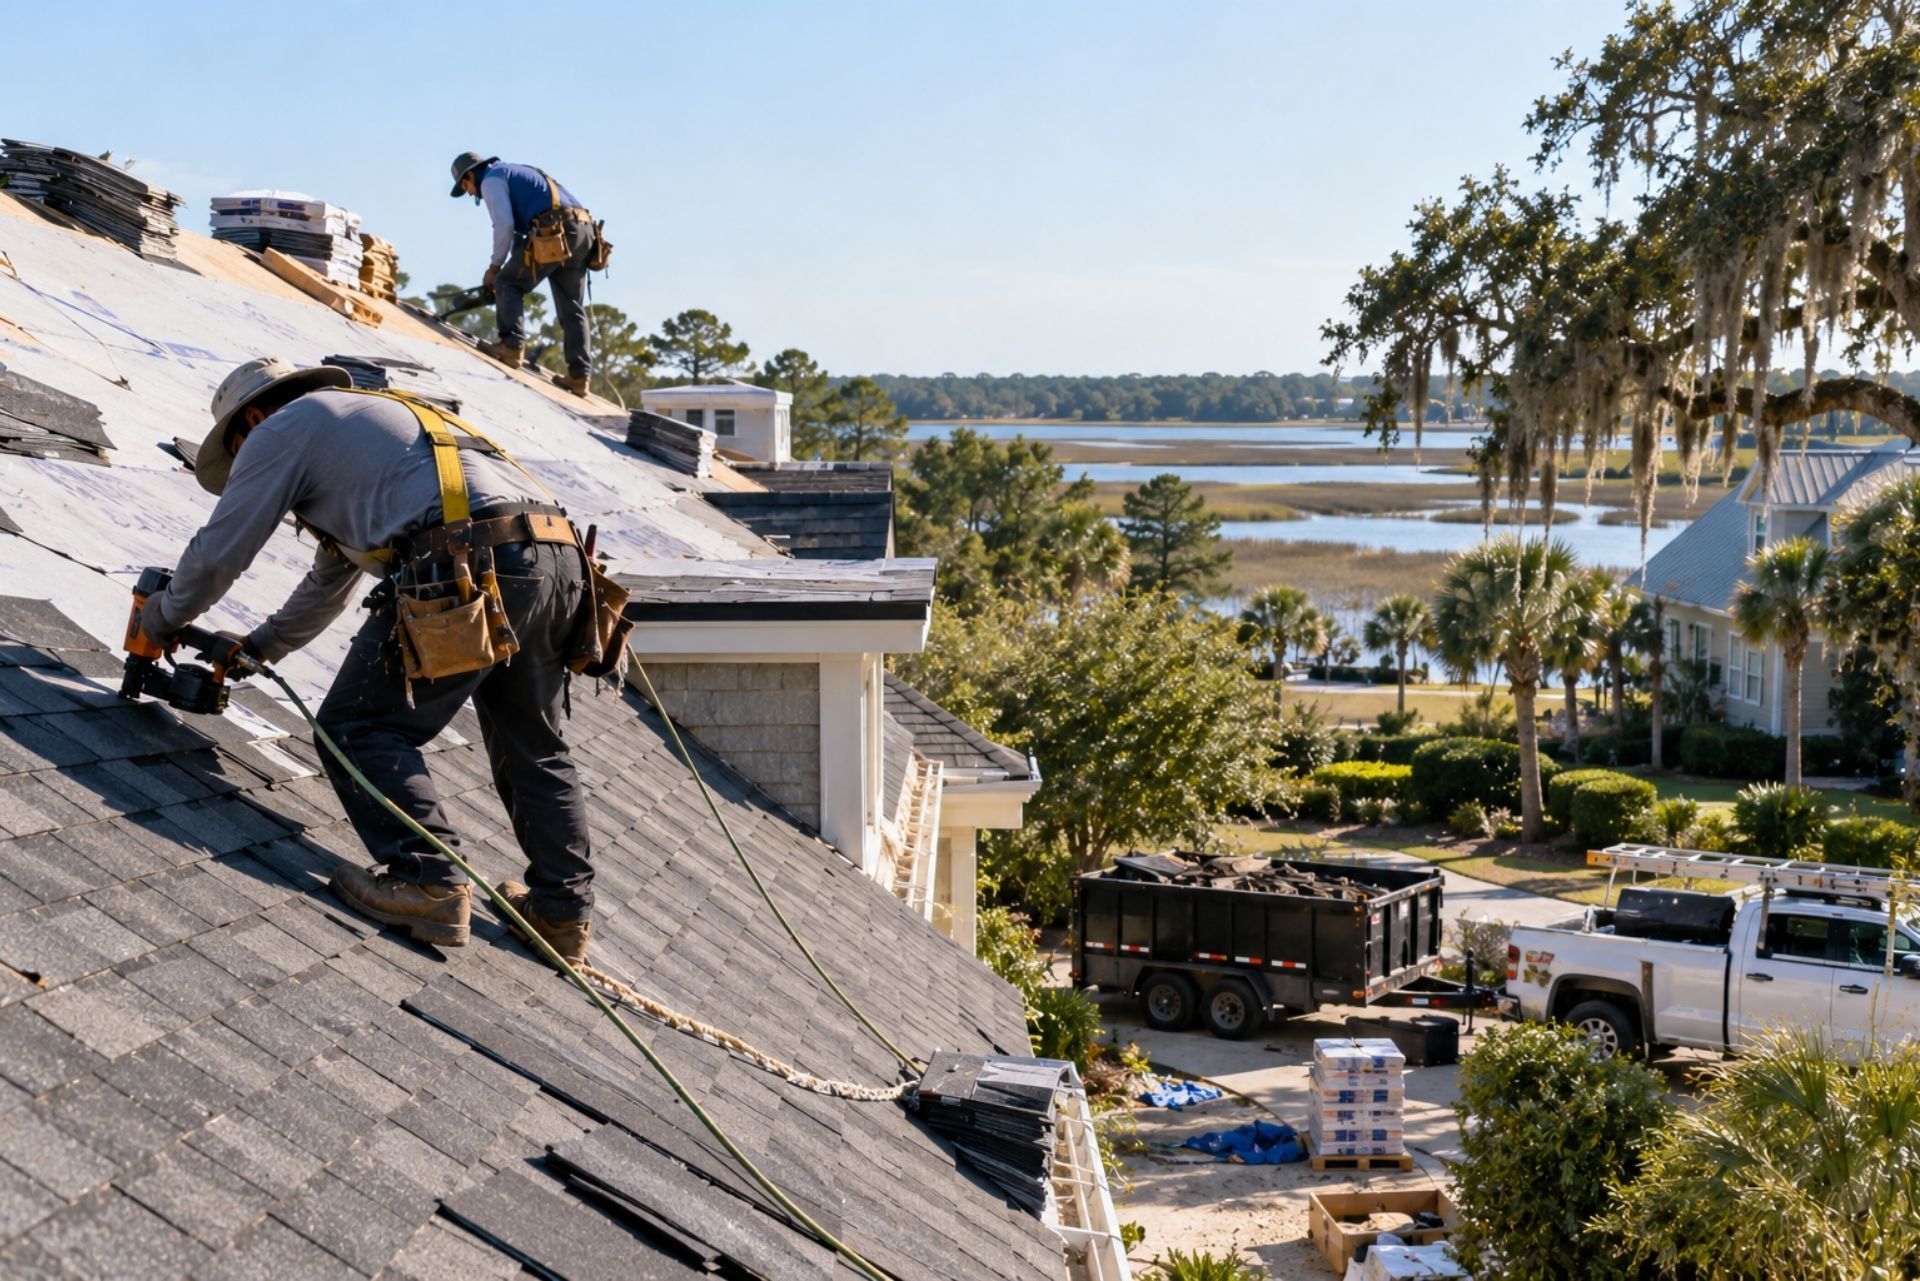
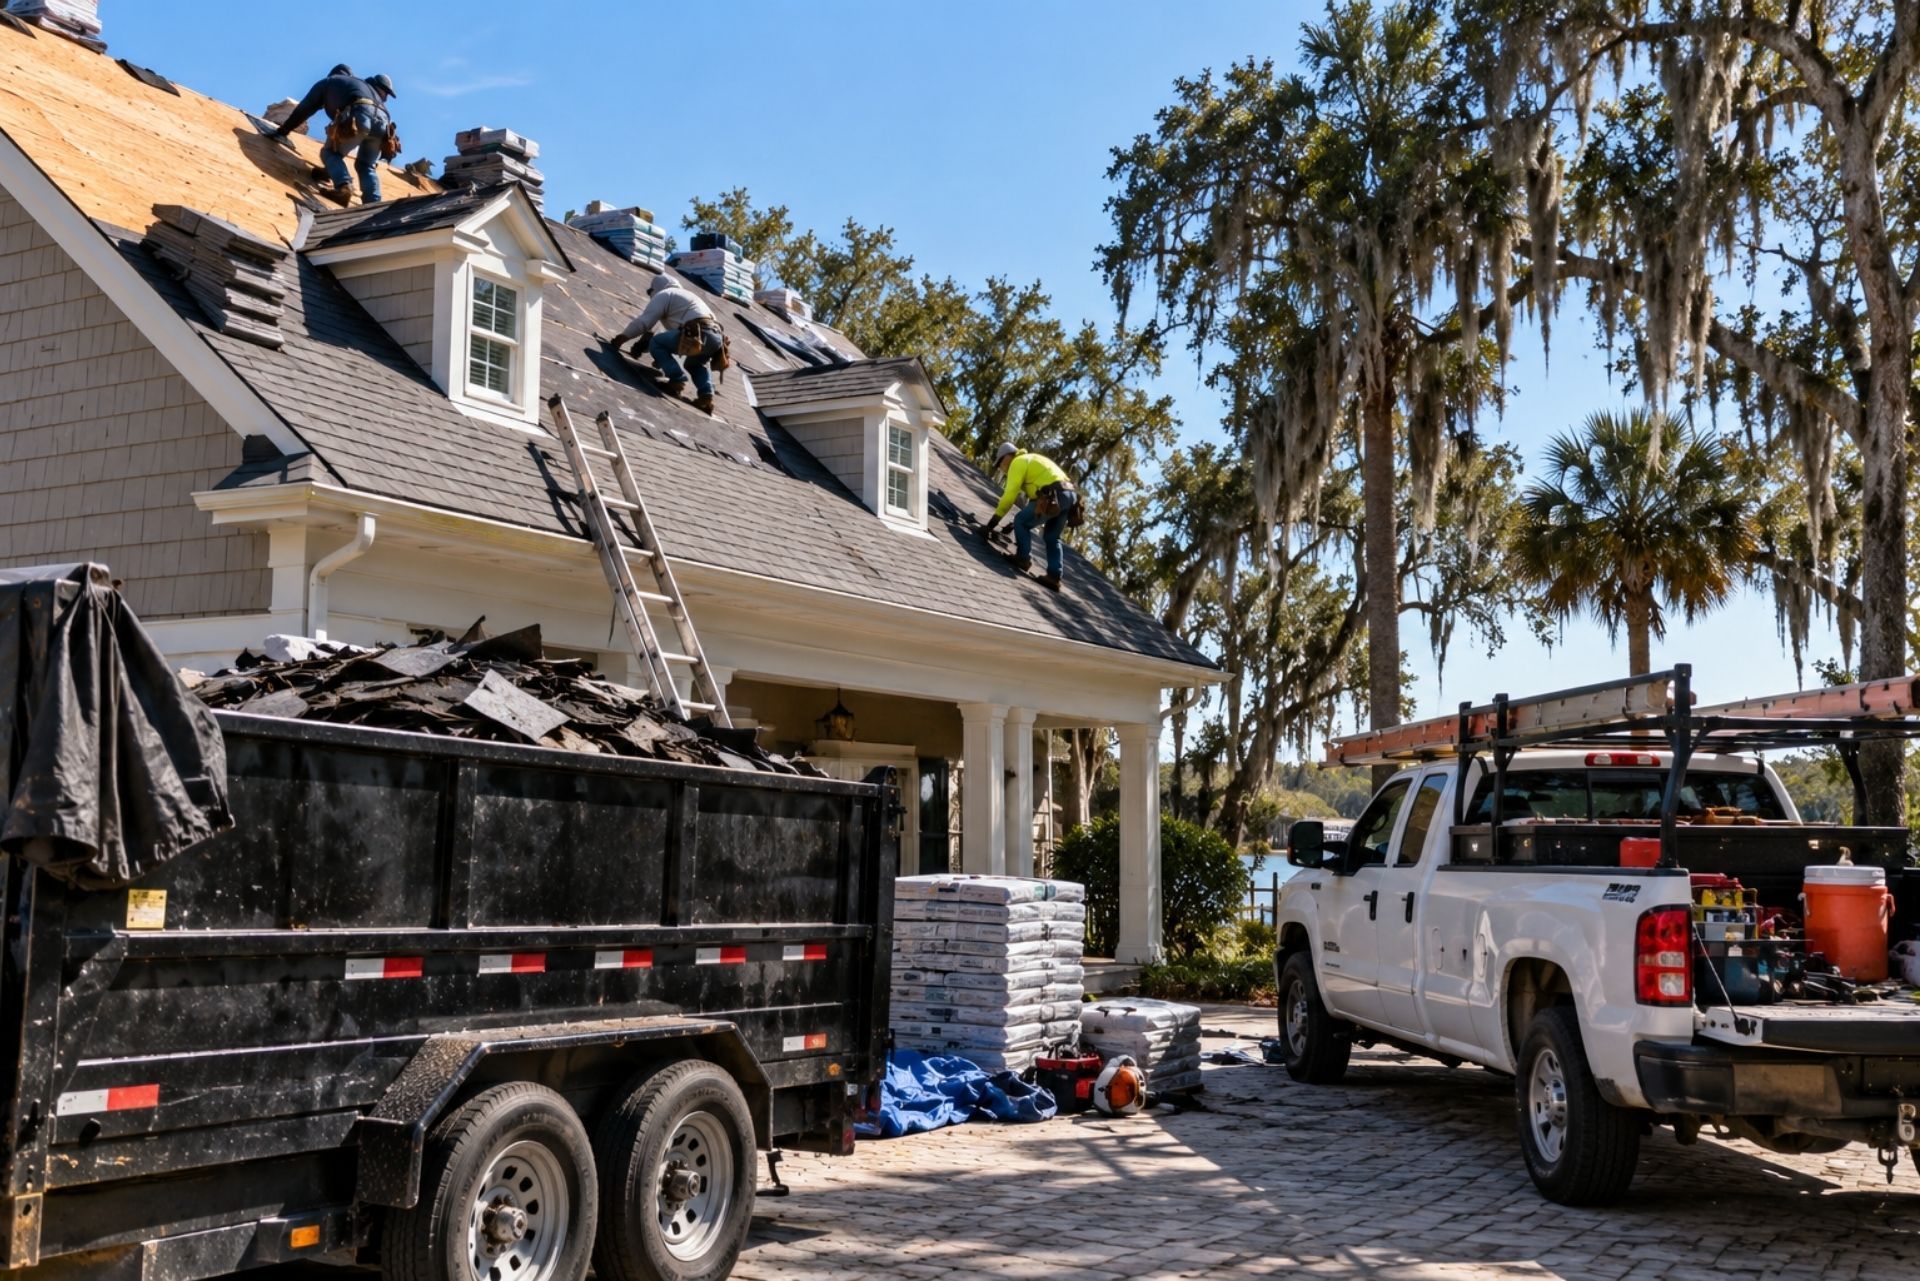
A roofing crew in Myrtle Beach finishes a tear-off on a Tuesday afternoon, and by Wednesday morning, the homeowner is calling about water damage from an overnight storm. A subcontractor in Columbia drops a bundle of shingles onto a parked car. A worker in Rock Hill slips off a ridge cap and breaks his collarbone. These aren't hypothetical situations: they're the kinds of claims that South Carolina roofing contractors deal with every season. And whether you're a one-truck operation or running multiple crews across the Palmetto State, having the right insurance setup is the difference between surviving a bad week and closing your doors. Roofing contractor insurance in South Carolina involves a tangle of general liability requirements, workers' comp class codes, policy exclusions, and certificate demands from general contractors and property managers. Getting any one of these wrong can leave you exposed at exactly the wrong moment. The coastal wind exposure, hurricane season, and high volume of storm damage work across the state make this an especially tricky market to insure. This guide breaks down the specific coverages, costs, exclusions, and class codes that matter most to South Carolina roofers in 2026.
Essential Insurance Coverages for South Carolina Roofers
Every
roofing business in South Carolina needs a core set of policies before bidding on a single job. The three non-negotiables are general liability,
workers' compensation, and
inland marine coverage. Each one protects a different part of your operation, and gaps between them are where most financial disasters happen.
General Liability and the Open Roof Clause
General liability covers third-party bodily injury and property damage: the shingles that dent a neighbor's car, the customer who trips over your materials. For roofers, the policy language around "completed operations" is critical because it covers damage that shows up after you've left the jobsite. A leak that develops six months post-installation falls under this portion of your GL policy.
The "open roof clause" is something every South Carolina roofer should understand. Many GL policies include language that excludes coverage for water damage to a structure's interior while the roof is open or partially removed. If a summer thunderstorm rolls through Florence while your crew has the decking exposed, and the homeowner's living room gets soaked, your policy might not pay that claim. Some carriers offer endorsements to cover this gap, but you have to ask for it specifically. It's one of the most common coverage blind spots in the roofing industry.
Workers' Compensation Laws in the Palmetto State
South Carolina requires workers' compensation insurance for any business with four or more employees. That threshold catches a lot of roofing companies off guard: even if you run a small crew, the moment you hit four workers (including yourself in some cases), you need a policy. The South Carolina Department of Labor, Licensing and Regulation handles contractor licensing and can verify compliance.
Roofing is one of the highest-risk trades for workers' comp purposes. Premiums reflect that risk directly, and we'll get into the specific class codes and rates below. One thing to keep in mind: even if you have fewer than four employees, many general contractors and property managers will refuse to hire you without a workers' comp certificate. So the legal minimum and the practical minimum are often different numbers.
Inland Marine: Protecting Tools and Equipment
Your commercial auto policy covers your trucks. Your GL covers liability. But what about the $15,000 worth of nail guns, compressors, ladders, and material hoists sitting in your trailer overnight? Inland marine insurance covers tools and equipment in transit or stored at jobsites. A standard business property policy typically only covers items at your listed business location, not spread across three different rooftops in the Lowcountry.
For roofers, inland marine is especially important because equipment theft from jobsites and trailers is common. A policy with a $500 deductible and $50,000 in coverage might run $400 to $800 per year: a fraction of what it costs to replace stolen equipment out of pocket.
Your CSP agent
Lawson Walker, CIC
Insurance Sales
On this page
CSP Insurance Services is a fully licensed independent insurance agency serving individuals, families, and businesses across South Carolina.
From our home in Florence, we proudly serve clients in Florence, Myrtle Beach, Rock Hill, Columbia, and communities throughout South Carolina. As an independent Trusted Choice agency, our team works with a wide range of top-rated carriers to provide personal and commercial coverage — home, auto, business, life, and more — tailored to the real needs of the people and businesses we protect.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Businesses increasingly rely on portable tech: laptops, tablets, external drives, and mobile servers. A computer equipment floater covers these items when employees take them off-site, whether that's a sales rep carrying a laptop to a client meeting in Columbia or a nonprofit transporting presentation equipment to a fundraiser. Some policies even cover the cost of data restoration, which can be more expensive than the hardware itself.
Understanding Roofing Exclusions and Policy Limitations
The coverage you don't have matters just as much as the coverage you do. Roofing policies are full of exclusions that can void a claim entirely if you're not paying attention.
Common Exclusions: Height Limits and Multi-Family Projects
Many general liability policies written for roofing contractors include height limitations. A policy might cover work up to two stories but exclude anything above three stories. If your crew takes on a commercial job involving a four-story building and someone gets hurt, you could be looking at an uncovered claim.
Multi-family dwelling exclusions are another trap. Some carriers will insure single-family residential roofing but exclude apartment complexes, condos, or townhome communities. South Carolina's coastal markets, particularly around Myrtle Beach and Hilton Head, have a huge volume of multi-family properties needing storm damage repairs. Roofers who work on storm-damaged properties across the state need to verify their policy doesn't exclude the exact type of work they're bidding on.
Subcontractor Vicarious Liability Issues
If you hire subcontractors and they cause damage or get injured, your insurance may be on the hook. This is called vicarious liability, and it's a major concern for roofing companies that scale up by using sub crews. Your GL policy might respond to a claim caused by an uninsured sub, but your workers' comp carrier will almost certainly charge you additional premium for any uninsured subcontractors.
The fix is straightforward but requires discipline: collect certificates of insurance from every subcontractor before they set foot on a jobsite. Verify that their coverage is current and that the limits meet your contract requirements. An independent agency like CSP Insurance Services can help you set up a system for tracking sub certificates so nothing slips through the cracks.
Workers' Comp Class Codes for Roofing Operations
Workers' compensation premiums in South Carolina are calculated using class codes assigned by the National Council on Compensation Insurance (NCCI). Your class code determines your base rate, and for roofers, these rates are among the highest of any trade.
Code 5551 vs. Code 5538: Residential and Commercial Differences
Class code 5551 applies to roofing operations, and it's the code most South Carolina roofing contractors will be assigned. The loss cost rates for code 5551 start at approximately $7.45 per $100 of payroll, though your actual carrier rate will be higher once the insurer adds their profit and expense loading. For a crew with $300,000 in annual payroll, that translates to a workers' comp premium that can easily exceed $25,000 per year before experience modification adjustments.
Class code 5538 covers sheet metal work, including metal roofing installation. If your company primarily installs standing seam or metal panel roofing systems, you might qualify for this code, which typically carries a lower rate than 5551. The distinction matters: getting classified under the wrong code can mean thousands of dollars in overpaid (or underpaid) premium.
South Carolina's statutory workers' comp rate schedules are published annually and provide a baseline for what employers should expect to pay.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Comparison: Basic vs. Comprehensive Roofing Coverage
Here's a side-by-side look at what a minimal insurance setup covers versus a more complete package:
| Coverage Area | Basic Package | Comprehensive Package |
|---|---|---|
| General Liability | $1M per occurrence / $2M aggregate | $1M per occurrence / $2M aggregate |
| Completed Operations | Included | Included with extended reporting |
| Open Roof Endorsement | Not included | Included |
| Workers' Compensation | Statutory minimums | Statutory minimums + employer's liability |
| Inland Marine | Not included | $50,000-$100,000 tool/equipment coverage |
| Commercial Auto | Liability only | Liability + physical damage + hired/non-owned |
| Umbrella/Excess | None | $1M-$5M excess liability |
| Height Limitation | 2 stories max | 3+ stories |
| Multi-Family Exclusion | Yes, excluded | No exclusion |
The basic package keeps you legal. The comprehensive package keeps you in business when something goes wrong on a big job. Most experienced roofers who've been through a serious claim will tell you the upgrade is worth every dollar.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Managing Certificates of Insurance (COI) for Clients
Every general contractor, property manager, and HOA in South Carolina is going to ask for a certificate of insurance before you start work. A COI is a one-page summary of your active policies, issued by your insurance carrier or agent. It proves you carry the required coverages and lists the certificate holder (usually the party hiring you) as an additional insured.
Getting COIs issued quickly matters. A slow turnaround on certificates can cost you jobs, especially during storm season when demand spikes and GCs are choosing between multiple subs. Roofers should verify their credentials and insurance documentation are current and easy to produce on short notice. Working with an agency that can issue same-day certificates, like CSP Insurance Services, eliminates a common bottleneck that costs roofers real revenue.
Keep a digital copy of your current COI on your phone. You'll need it more often than you think. Understanding what each section of a certificate means helps you catch errors before they become problems on a jobsite.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Factors Influencing Insurance Costs in South Carolina
Your premium isn't a random number. Several factors push roofing insurance costs up or down in South Carolina:
- Payroll size: Workers' comp is calculated as a rate per $100 of payroll. More employees or higher wages mean higher premiums.
- Claims history: Your experience modification rate (EMR or mod rate) adjusts your workers' comp premium based on your past claims. An EMR above 1.0 means you're paying more than average; below 1.0 means you're getting a discount.
- Types of roofing work: Steep-slope residential, flat commercial, metal panel, and tile all carry different risk profiles. A company doing mostly flat commercial work may pay differently than one focused on residential shingle replacement.
- Geographic territory: Coastal counties from Georgetown to Beaufort face higher wind and hail exposure, which can affect GL and property rates.
- Subcontractor usage: Uninsured subs get added to your payroll for workers' comp calculation purposes, inflating your premium significantly.
- Revenue volume: GL premiums are often based on gross receipts. A $2 million revenue roofing company pays more than a $500,000 operation.
South Carolina's ongoing legislative discussions around roofing fraud investigations also signal that regulators are paying closer attention to the industry, which could affect insurance requirements and enforcement going forward.
Specialty Lines: Flood, Earthquake, and Valuable Items
Flood insurance is a separate policy, typically written through FEMA's National Flood Insurance Program or a private carrier. If your home sits in a designated flood zone anywhere along the SC coast or near inland rivers, your mortgage lender will require it. But even homes outside mapped flood zones can flood: roughly 25% of flood claims come from properties in low-to-moderate risk areas.
Earthquake coverage is less common in South Carolina, but the state sits near the Charleston fault zone, which produced a magnitude 7.3 quake in 1886. A rider or standalone earthquake policy is worth considering if you're in the Lowcountry.
Scheduled personal property endorsements cover high-value items like jewelry, art, firearms, or musical instruments that exceed standard policy sub-limits. Most homeowners policies cap jewelry coverage at $1,500-$2,500 per item. If your engagement ring is worth $8,000, you need a scheduled endorsement or inland marine floater to cover the difference.
Common Questions About South Carolina Roofing Insurance
Do I need workers' comp if I only have two employees? South Carolina law requires workers' comp at four or more employees. But many GCs won't hire you without it regardless of your crew size, so carrying a policy even below the threshold is common practice.
Can I use my personal auto insurance for my work truck? No. Personal auto policies exclude commercial use. If you're hauling materials or driving to jobsites, you need a commercial auto policy.
What happens if my subcontractor doesn't have insurance? Your workers' comp carrier will add the sub's payroll to your policy and charge you accordingly. Your GL policy may also respond to claims caused by uninsured subs, raising your future premiums.
How often should I update my COI? Every time your policy renews, changes, or a new certificate holder needs to be added. Most policies renew annually, so at minimum you're updating once a year.
Does my GL policy cover work I did last year? If you have a "claims-made" policy, it only covers claims reported during the policy period. An "occurrence" policy covers incidents that happened during the policy period, even if the claim comes later. Most roofing GL policies are occurrence-based, but always confirm.
Are there specific South Carolina licensing requirements for roofers? Yes. Roofing contractors in South Carolina must be licensed through the SC Contractors' Licensing Board, and proof of insurance is part of the licensing process.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
Boat and Watercraft Coverage for Weekend Adventures
Your homeowners policy might cover a small kayak or canoe, but anything with a motor typically needs its own policy. Boat insurance covers physical damage to the vessel, liability for injuries or property damage you cause on the water, and sometimes towing and salvage costs.
Lake-specific risks differ from coastal ones. A boat kept at Myrtle Beach faces saltwater corrosion, hurricane exposure, and higher theft rates than one stored at a private dock on Lake Wateree. Your policy should reflect where you keep and operate the boat. An independent agency like CSP Insurance Services can compare quotes across multiple marine carriers to find coverage that actually matches your boating habits rather than forcing you into a one-size-fits-all plan.
| Feature | Admitted (Standard) Carriers | Non-Admitted (E&S) Carriers |
|---|---|---|
| State regulation | Fully regulated; rates filed with state | Exempt from rate filing; flexible pricing |
| Guaranty fund protection | Yes: state fund covers claims if carrier fails | No: no guaranty fund backstop |
| Policy forms | Standardized (ISO forms common) | Manuscript or custom forms |
| Risk appetite | Prefers low-to-moderate risk | Accepts high-risk and unusual exposures |
| Premium cost | Generally lower | Typically 20-75% higher |
| Surplus lines tax | Not applicable | Buyer pays state surplus lines tax (varies 2-5%) |
| Speed of placement | Standard timelines | Can be faster or slower depending on complexity |
Making the Right Choice for Your Roofing Business
Getting roofing insurance right in South Carolina requires more than just buying the cheapest policy you can find. The exclusions, class codes, and certificate requirements are specific enough that a generic business policy won't cut it. You need coverage built around how roofing actually works: the height risks, the open-roof exposure, the subcontractor relationships, and the coastal weather that makes every season unpredictable.
The smartest move is working with an independent agency that understands roofing operations and can compare options across multiple carriers. CSP Insurance Services has been helping South Carolina businesses find the right coverage since 1939, and their team can walk you through the specific policy language that matters for your operation. No call centers, no chatbots: just direct access to people who know the industry.
If you're starting a new roofing company, renewing an existing policy, or just want to make sure you're not overpaying for gaps in coverage, request a quote and get a policy review tailored to your business. The five minutes it takes could save you from a six-figure mistake.
About the author
Lawson Walker, CIC
I'm proud to be part of an agency that's served Florence since 1939. CSP Insurance Services started as Cormell-Streett & Patterson, built by people who believed insurance should be personal — and more than eight decades later, that conviction still drives everything we do. Commitment, Service, Protection isn't just what CSP stands for; it's how I approach every client relationship.
As an independent, Trusted Choice agency, we aren't tied to any single carrier. That means I work for you — shopping multiple companies to match you with coverage that actually fits your family, your business, and your budget. No call centers, no chatbots. Just a local expert who takes the time to understand what matters to you and stands by you when it counts.
Whether you're protecting your home, your car, or a business you've spent years building, I'd be glad to help you find the right coverage.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Most Requested
Core business coverage.
The policies most South Carolina businesses start with.
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Workers Compensation
Required for most South Carolina employers with staff. It covers medical bills and lost wages when an employee is hurt on the job.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
General Liability
Accidents happen on the job and on your property. General liability covers third-party injury and property damage claims against your business.
Inland Marine
Tools, equipment, and goods on the move aren’t covered by standard property policies. Inland marine protects them wherever they travel.
Business Owners (BOP)
A business owners policy bundles property and liability coverage into one package, often at a better price for small businesses.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Personal Insurance
Coverage for your home, vehicles, and family.
Protect what matters most with personal policies shopped across our carriers.
Home
Your house is likely your largest investment. Home insurance helps rebuild after covered damage and protects you from liability.
Auto
South Carolina drivers need real protection. Auto coverage handles liability, collision, medical costs, and uninsured drivers.
Umbrella
When a serious claim climbs past your home or auto limits, umbrella coverage adds an extra layer of liability protection.
Boat
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Condo
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Industries We Serve
Specialized coverage for your industry.
Every industry carries its own risk. We help South Carolina businesses protect what they've built.
Restaurants
Kitchens, customers, and staff create daily exposure. We protect your property, equipment, liquor liability, and employees.
Manufacturers
From equipment breakdown to product liability, manufacturers face risk on the floor and beyond. We help cover property, machinery, and goods.
Healthcare Providers
Practices and clinics carry patient, property, and professional risk. We help cover liability, equipment, and the people who run your practice.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Commercial Property
Protect the building, equipment, and inventory your business runs on, so a covered fire, theft, or storm doesn’t become a closed door.
Commercial Auto
Cars, trucks, and fleets used for work need more than a personal policy. This handles liability, damage, and your drivers.
How It Works
Getting covered is simple.
Four steps, one real person from start to finish.
We compare carriers
We shop options across our carriers to find strong protection at a fair price.
We compare several carriers to find a policy that fits you, not one company's products.
Multi-carrier choice
Claims advocacy
When a claim happens, we stand in your corner and help move it forward with your carrier.
Local SC roots
We live and work in Florence and understand the risks your community faces because we face them too.
Client Reviews
Why clients choose CSP.
Independent advice, real people, and decades of local roots.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
FAQs
Questions, answered.
Straight answers about working with an independent agency.
What does an independent insurance agency do?
An independent agency represents several carriers instead of one. We compare coverage and pricing across companies, then recommend the policy that fits you best.
Do you cover both personal and business insurance?
Yes. CSP writes personal lines like home and auto, and commercial lines for businesses across South Carolina.
How long has CSP been in business?
CSP traces its roots to 1939, with more than 80 years serving South Carolina families and businesses.
Will I work with a real person?
Always. No call centers and no chatbots — you work with a local team member who knows your account.
Which areas do you serve?
We’re based in Florence and serve clients statewide, including Myrtle Beach, Rock Hill, and Columbia.
How do I get a quote?
Request a quote online, call us, or stop by the office. A real person will review your needs and follow up.
How It Works
Insurance tips & updates.
Plain-language guidance to help you make confident decisions.
We compare several carriers to find a policy that fits you, not one company's products.
◆
80+ years local experience
1939
Serving SC
Insurance Sales
J. Roger Jordan, CIC
[CONFIRM bio]
Boat
Your association covers the building, but not what’s inside. Condo insurance protects your belongings, improvements, and liability.
Time on the water should be worry-free. Boat coverage protects your vessel, your passengers, and your liability on the lake or coast.
Condo
Motorcycle
Riders need coverage built for the road. Motorcycle insurance protects your bike, your gear, and you after an accident.
Get a Quote
Let's find your coverage.
Tell us a little about what you need to protect. A real person from our Florence team will review it and follow up.
2420 Hoffmeyer Road, Suite D
Florence, SC 29501
Mon–Fri 8:30am – 5:00pm